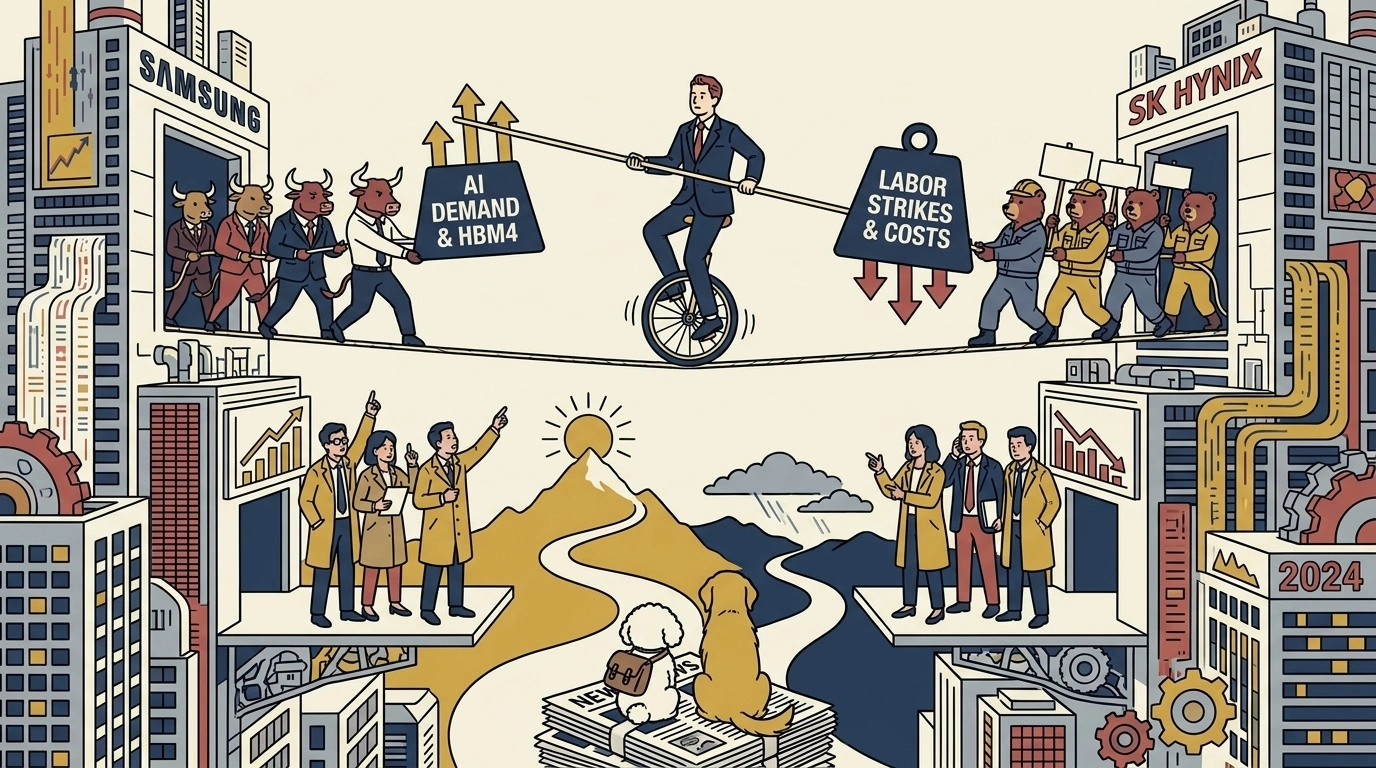
Amid ongoing rosy outlooks from the brokerage industry for domestic semiconductor bellwethers Samsung Electronics and SK Hynix, analysts' expectations and views have recently begun to diverge slightly, drawing market attention.
First, regarding SK Hynix, an unusually downgraded investment rating report emerged among domestic securities firms. While 24 out of 25 major securities firms competitively maintained a 'Buy' rating and raised their target prices to around 2 million won, BNK Investment & Securities was the only one to downgrade its investment rating from 'Buy' to 'Hold' on April 27. BNK Investment & Securities evaluated that although first-quarter operating profit and revenue reached record highs for a single quarter, they failed to meet the market's heightened expectations. In addition, it analyzed that in the second half of the year, the inference artificial intelligence (AI) cycle that has continued since last year will enter its latter half, and as the revenue proportion of the relatively less profitable HBM4 expands, stock price momentum could slow down.
Regarding Samsung Electronics, the directions of target prices from foreign investment banks (IBs) were sharply divided, but both firms commonly pointed to the 'labor strike' as a downside risk to short-term earnings.
Citi Securities lowered its target price for Samsung Electronics from 320,000 won to 300,000 won. Citi Securities agreed with the positive memory fundamental analysis that Agentic AI is driving memory demand, leading to a record low supply-to-demand fulfillment rate, and that supply shortages will further intensify in 2027. However, it expressed concerns that amidst the worsening union strike, performance bonus-related provisions not yet reflected in the first-quarter earnings will drag down future performance. Through its report, Citi Securities stated, "While we view Samsung Electronics as a long-term beneficiary of the memory market growth, we are concerned about the earnings downside risk caused by performance bonus-related provisions amid the intensifying labor strike. " It forecast that these provisions would take a toll on operating profit estimates for 2026 and 2027, eroding earnings by 10% and 11%, respectively. Along with this, while presenting a base target price of 300,000 won, Citi Securities reportedly left open the possibility of up to 350,000 won in a bull case scenario and down to 150,000 won in a bear case scenario.
On the other hand, JPMorgan presented a strongly optimistic view, raising its earnings per share (EPS) forecasts for Samsung Electronics by 31~33% and increasing its target price to 350,000 won. JPMorgan diagnosed that AI workload memory demand is spreading from traditional GPUs to CPUs, and the value of NAND is also rising due to a surge in demand for KV cache offloading. In addition, it highly evaluated the fact that Samsung Electronics has begun mass production of HBM4, is about to ship HBM4E customer samples at the end of the second quarter, and has secured sustainable free cash flow (FCF) by signing long-term agreements (LTAs) with some clients.
However, even amid this bullish outlook, JPMorgan also added a conservative view on the labor strike. JPMorgan acknowledged the possibility of a short-term negative factor, stating, "The possibility of ongoing labor wage increases leaves a potential downside risk to our SG&A (selling, general, and administrative expenses) outlook. Until the concerns over the labor strike are resolved, we do not rule out the possibility that Samsung Electronics' stock price will underperform memory peers in the short term." However, unlike Citi Securities, it interpreted this as an active investment opportunity, recommending, "Our mid-to-long-term fundamental view on the company and its stock price is independent of the aforementioned labor strike, and we will use any weakness as a buying opportunity."
As such, the perspectives of the brokerage industry are sharply divided depending on how individual risks are interpreted, including the timing of entering the latter half of the semiconductor industry cycle, HBM margin forecasts, and the possibility of earnings damage from the labor strike. As stock prices have been on an upward trajectory day after day, it is now a time that requires investors to more carefully distinguish the wheat from the chaff by meticulously scrutinizing the rationales of both sides.
Company financial data, investment reports, and startup analysis — all in one place
Explore PitchdeckCurated news, every week — straight to your inbox
Every Friday · Unsubscribe anytime