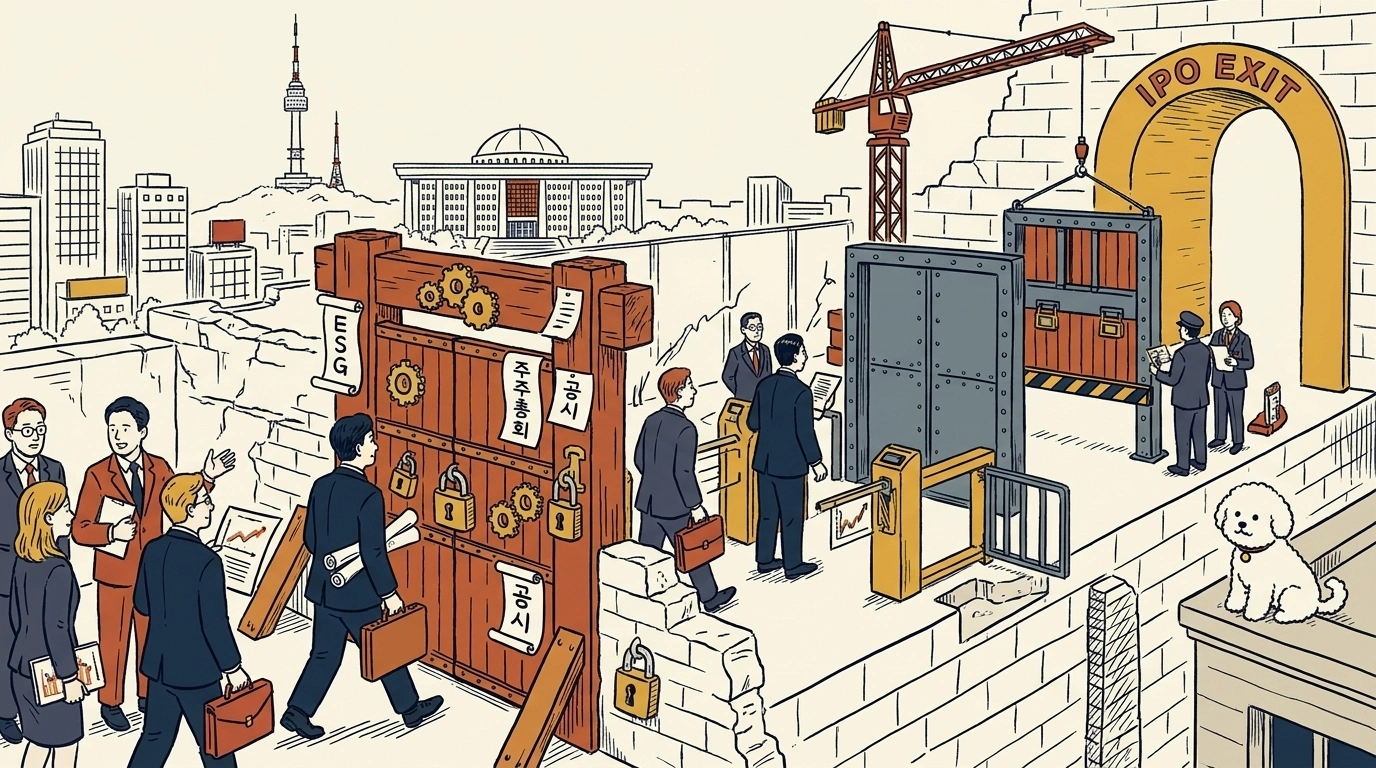
The exit paths for private equity (PE) funds and strategic investors (SI), who realize value by listing subsidiaries carved out through physical divisions, have narrowed on multiple fronts in just a month. Starting with Representative Park Hong-bae's proposal to establish a voting quorum for physical divisions on June 11, seven amendments to the Financial Investment Services and Capital Markets Act have been submitted to the National Policy Committee over four weeks. From the passing quorum of division agendas to the operation of the general shareholders' meetings where the voting takes place, and disclosures by listed companies — new provisions have been added at every corner of the exit paths.
The seven bills are not scattered regulations but point in one direction. They are grouped into five branches: value-up disclosures, ESG, operation of general shareholders' meetings, employee stock ownership, and securities firms' margin trading, with the balance shifting entirely toward minority shareholders and retail investors. Costs for disclosure and general meeting operations for listed companies, exit design variables for PE/SIs, credit business margins for securities firms, and information access rights for retail investors are all moving simultaneously in different provisions. This is a phase where listed companies, PEs, securities firms, and retail investors must recalculate their respective costs.
4 Weeks, 5 Axes — The Five Proposed Branches
If the amendments to the Capital Markets Act received by the National Policy Committee from June 16 to July 7 are arranged in the order of proposal dates, five axes emerge.
Proposal Date | Lawmaker | Revised Provisions | Key Point |
|---|---|---|---|
6/16 | Lee Hoon-ki (DP, Incheon Namdong-eul) | Newly establishes Article 161-2 | Mandates submission of corporate value enhancement (value-up) plans for listed companies with a PBR below 1 for two or more consecutive years — Direct aim at the Korea Discount |
6/18 | Kim Hyun-jung (DP, Pyeongtaek-byeong) | Articles 159, 159-2, 160 | Mandates disclosure of ESG and sustainability information — Blocks greenwashing |
6/22 | Lee Kang-il (DP, Cheongju Sangdang) | Newly establishes Articles 165-18 to 165-20 | General shareholders' meeting operation reform — Direct aim at practices of concentrated holding, rushed convocation notices, and director absenteeism, pre-disclosure of voting results for cumulative voting |
7/1 | Park Hong-bae (DP, Proportional) | Article 165-7 | Increases priority allocation ratio for employee stock ownership associations from 20% to 30% |
7/7 | Cho In-chul (DP, Gwangju Seo-gu A) | Article 72 | Mandates disclosure of the rationale for calculating interest rates on securities firms' collateralized loans for sales proceeds — Protection of retail investors |
The five axes do not have overlapping targets. The Lee Hoon-ki bill elevates the value-up plans of undervalued listed companies to a written obligation, and the Kim Hyun-jung bill newly establishes disclosure obligations for non-financial information. The Lee Kang-il bill touches upon the operating rules of general shareholders' meetings themselves, the Park Hong-bae bill addresses the pathways for employees to acquire equity, and the Cho In-chul bill tackles the price transparency of securities firms' margin trading. Within a four-week period of a single session, five provision areas of the one Capital Markets Act have simultaneously become targets for amendment.
The Lee Kang-il Bill Directly Expands on the June 16 Article
Among the five axes, the Lee Kang-il bill (June 22, establishing three provisions including Article 165-18) tackles the same issue as the Park Hong-bae bill covered on this page on June 16, but from the opposite end of the voting procedure. If the Park Hong-bae bill narrowed the "passing quorum" for physical division agendas toward minority shareholders, the Lee Kang-il bill revises the "operating rules" of the general shareholders' meeting where that vote takes place.
The Lee Kang-il bill targets the practices of concentrating regular general shareholders' meetings at specific times, rushed convocation notices, and director absenteeism, and requires the disclosure of the results of advance voting by the day before the general meeting when electing directors through cumulative voting. In order for minority shareholders to organize votes on structural change agendas like physical divisions, directors to explain the decision must be present (attendance), time to review the agenda must be secured (convocation notice), and the landscape of cumulative voting must be readable in advance (prior disclosure). The minority shareholder veto power created by the Park Hong-bae bill on June 16 operates as an actual vote when these requirements back it up. Thus, a bill to narrow the quorum and a bill to open up the operation of general meetings have been submitted to the same standing committee with a four-week interval.
Proposals tackling the same issue from the "timing" of information disclosure have also ridden this wave. On June 15, the day before the value-up bill, Rep. Lee Hoon-ki proposed an amendment to the Capital Markets Act (Article 159) that moves forward the submission and disclosure of listed companies' business reports by six weeks prior to the regular general shareholders' meeting. This provision buys time for shareholders to review the company's financial and governance information before voting, and it pairs with an amendment to the Commercial Act that extends the deadline for general meeting convocation notices from two weeks to six weeks prior. In effect, one lawmaker proposed bills regarding value-up and the provision of general meeting information over the course of a week.
Living up to the Series Name — Park Hong-bae Proposes a Second Bill
On July 1, Rep. Park Hong-bae himself proposed an amendment to the Capital Markets Act again. Following the physical division quorum bill on June 11, this time it is a proposal to increase the priority allocation ratio for employee stock ownership associations under Article 165-7 from 20% to 30%.
The direction of both proposals is connected as one. While the physical division quorum bill dealt with the authority of minority shareholders to 'block' structural changes, the expansion of employee stock allocation widens the pathway for workers to 'acquire' equity. The two axes of minority shareholder protection and worker asset formation were encapsulated into the Capital Markets Act by the same lawmaker a month apart. The Park Hong-bae line that began on this page on June 16 is continuing with the proposer's own second bill.
The Costs Recalculated by the Five Axes
Listed Companies — Burden of Disclosures and General Meeting Operations. Lee Hoon-ki's value-up plan, Kim Hyun-jung's ESG disclosure, and Lee Kang-il's general meeting operation requirements all point toward increasing the disclosure and governance costs borne by listed companies. If all three bills pass together, the written obligations will concentrate more heavily on listed companies experiencing prolonged undervaluation.
PE/SI — Exit Design Variables. As pointed out on June 16, the value realization model premised on a subsidiary IPO after a physical division will have a lower probability of passage due to Park Hong-bae's quorum bill. If Lee Kang-il's general meeting operation reform is added to this, the room for minority shareholders to organize at the general meeting itself where the division vote occurs grows larger. The axes requiring a re-estimation of the passage margin for exit scenarios have increased from one to two.
Securities Firms/Retail Investors — Price Transparency of Margin Trading. Cho In-chul's bill (Article 72) includes the rationale for calculating the interest rates on securities firms' collateralized loans for sales proceeds as a subject of disclosure. If the margin structure of the credit business is revealed to retail investors, the baseline for interest rate competition among securities firms will change.
Possibility of Passage and Remaining Variables
All seven bills were proposed by lawmakers affiliated with the Democratic Party of Korea. However, minority shareholder protection and the improvement of listed companies' governance are not so much partisan issues, but rather a policy track already opened up by the government when it strengthened disclosures and listing reviews for physical divisions in 2022 and introduced appraisal rights for dissenting shareholders through an enforcement decree on December 27 of the same year. These four weeks of bills expand the points of intervention upon that foundation to include value-up, ESG, general meetings, employee stock ownership, and margin trading. The real variables are the review schedule and the response from the business community.
During the review stage, there is room for the five axes to be individually merged or adjusted, and in particular, the mandate for value-up plans and general meeting operation requirements are directly linked to the burden on listed companies, making it highly likely that economic organizations will express their stances at the committee level. When the National Policy Committee jointly places these bills on the review table will directly reflect on the practical calendars for listed companies' disclosure and general meeting preparations, as well as PE/SI exit designs for the second half of this year.
The trend opened by a regulation targeting a single physical division has spread across all sections of the exit path in just four weeks. Listed companies, PEs, securities firms, and retail investors are already recalculating their costs in the provisions respectively touched upon by those seven bills.
This article was written based on Legiscope, the legislative tracking engine built by News Epoch.
Company financial data, investment reports, and startup analysis — all in one place
Explore PitchdeckCurated news, every week — straight to your inbox
Every Friday · Unsubscribe anytime