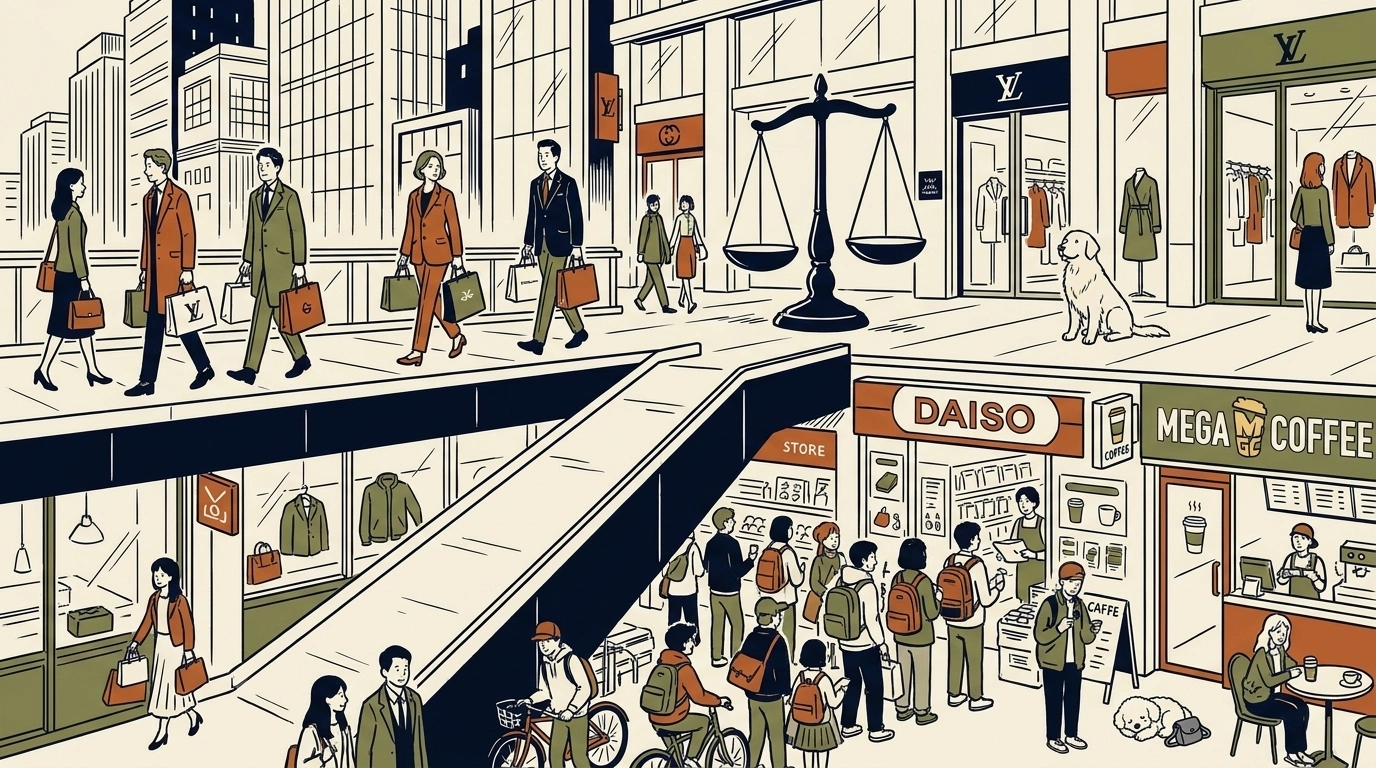
Low-Asset Class Faces Heavy Burden of Food and Housing Costs… Luxury and Cost-Effective Markets Grow Together
Two contrasting scenes are simultaneously unfolding in the Korean consumer market. On one side, luxury goods are growing rapidly, while on the other, brands leading with price competitiveness are doing the same.
Chanel Korea's sales in 2025 reached 2.0126 trillion won, surpassing Nike Korea's 1.8913 trillion won. Although the accounting periods of the two companies are different, meaning these figures do not compare the exact same timeframe, it is a symbolic result that shows the status luxury goods hold in the domestic consumer market.
On the opposite side, Daiso, Mega MGC Coffee, and UNIQLO are expanding their sizes. Asung Daiso's sales in 2025 increased by 14.3% compared to the previous year, and the sales of MGC Global, the operator of Mega MGC Coffee, rose by 30.4%. UNIQLO, operated by FRL Korea, also saw its sales for the 2025 fiscal year increase by 28%.
The Bank of Korea did not directly analyze the growth of luxury and cost-effective brands. Various factors, such as pricing policies, product competitiveness, store expansion, and marketing, affect the performance of individual companies. However, two recent BOK Issue Notes published by researchers at the Bank of Korea's Research Department present a macroeconomic background to understand the phenomenon of both the high-end and low-end markets growing together.
Different Assets Meant Different Amounts of Money Available for Consumption
BOK Issue Note No. 2026-14, 'The Reality and Repercussions of Household Polarization in Our Economy', assessed that Korean households are facing "complex polarization where a deepening wealth gap and a re-widening income gap intertwine."
The net worth Gini coefficient, which indicates the degree of wealth inequality, rose from 0.584 in 2017 to 0.625 in 2025. A Gini coefficient closer to 1 means more severe inequality. The proportion of net worth held by the top 10% of households also increased from 43.0% in 2022 to 46.1% in 2025.
The rise in real estate prices was pointed out as the core factor that widened the wealth gap. Households that own a home saw their net worth increase due to rising prices, while non-homeowning households simultaneously took on the burden of housing costs and higher home purchase prices.
The wealth gap even changed the composition of consumption. In the 2025 survey, the proportion of housing and food costs in total consumption was 41.8% for households in the top 20% of net worth, but it reached 57.1% for households in the bottom 20%.
Households with fewer assets must spend more than half of their income on making a living and housing costs. As they have less money left over, they are inevitably more sensitive to prices when choosing products. On the other hand, high-asset households have relatively more room to spend on discretionary consumption, such as luxury goods, leisure, and cultural activities, excluding essential expenses.
These figures do not directly prove the causes of the sales increases for Chanel or Daiso. However, they can serve as evidence explaining the simultaneous growth of the two markets, given that the high-asset class has growing room for discretionary consumption, while the low-asset class faces increasing constraints forcing them to weigh prices.
The Youth Who Cannot Climb the Asset Ladder Even with High Income
Recently, the income gap has been added to the wealth gap. The disposable income Gini coefficient, which had been falling thanks to the government's redistribution policies, rebounded slightly from 0.323 in 2023 to 0.325 in 2024.
Bank of Korea researchers pointed to the growth and wage gap between the IT manufacturing sector, including semiconductors, and the non-IT industry as the background. Their analysis suggests that while employment types like regular and non-regular workers were the main axis of the income gap in the past, recently, the industry in which one works is emerging as a new factor of inequality.
The gaps in assets and income reinforce each other. The high-income class can accumulate assets faster through savings and investments. Accumulated assets, in turn, generate dividends, interest, and rental income, widening the income gap. Conversely, households with fewer assets have less money available for savings and investment due to high housing costs.
In this process, the economic position of the youth has become particularly vulnerable. Among households in the bottom 20% for both net worth and income, the proportion accounted for by people in their 20s and 30s nearly doubled from 7.9% in 2020 to 15.2% in 2025.
The number of young people whose income is in the middle-to-upper range but whose assets remain in the lower range has also increased. This class is referred to overseas as 'HENRYs' (High Earners, Not Rich Yet). According to the Bank of Korea's analysis, the probability of young people aged 20 to 34 who are in the 1st and 2nd quintiles for net worth but the 3rd to 5th quintiles for income moving to upper asset classes has recently declined.
Even if the income earned from working is not small, it has become difficult to climb the ladder of asset formation as they fail to catch up with the speed of rising house prices. For them, cost-effective consumption is not just a simple preference but is closer to a financial choice to cover housing costs and save money for future home purchases.
The phenomenon of assets being tied up in the elderly population also slows down asset circulation. Real estate is concentrated among the elderly, and the net worth Gini coefficient within those in their 60s and older was 0.63, higher than the 0.54 for those in their 20s and 30s and 0.57 for those in their 40s and 50s.
If the so-called 'old-to-old inheritance', where elderly parents pass their wealth down to their elderly children, increases, assets cannot be transferred in a timely manner to the youth and middle-aged who need funds for home acquisition, education, and starting a business. In Japan, which experienced an aging population earlier, the proportion of those aged 80 and over among people leaving inheritances rose from about 40% in 1989 to over 70% in 2019.
Even if Stock Assets Increase by 10,000 Won, Consumption Grows by Only 130 Won
The reason why consumption does not increase as much as expected even when stock prices rise can also be found in asset distribution.
According to BOK Issue Note No. 2026-10, 'An Evaluation of the Stock Wealth Effect in Korea', it was estimated that when the value of stock assets held by a household increases by 10,000 won, consumption grows by about 130 won. This means the marginal propensity to consume regarding stock capital gains, the so-called stock wealth effect, is 1.3%.
In major developed countries such as the US and Europe, 3 to 4% of the increase in stock assets led to consumption. Japan, which has a relatively small wealth effect, also surpassed Korea with 2.2%.
There are three main reasons why Korea's stock wealth effect is small. First, the stock assets held by households are not large to begin with. As of 2024, the scale of stock assets compared to disposable income was 77.3% in Korea, falling significantly short of the US's 255.6% and the major European countries' average of 183.9%.
Even the stocks that are held are concentrated in the upper classes. 73.2% of total stock assets were held by households in the top 20% of net worth. The holding proportion of the top 20% in income also reached 64.5%.
Looking at the annual average stock capital gains from 2020 to 2024, households in the 5th quintile of net worth averaged 2.06 million won, while the rest of the households only saw 100,000 to 410,000 won. In other words, even if stock prices rose, the asset increase that the majority of households could experience was not large.
Low-income, low-asset households and the youth have a tendency to expand consumption relatively more when their assets increase. Since they lack cash flow, they are highly likely to spend on consumption they had delayed if capital gains occur.
On the other hand, high-income, high-asset households that hold many stocks already have sufficient consumption capacity, so they do not significantly expand consumption even if their assets increase further. The mismatch where the class with a large consumption response holds few stocks, and the class with many stocks has a small consumption response, is lowering the overall wealth effect.
Money Earned from Stocks Headed to Real Estate
The second reason is that it is difficult to trust the returns from domestic stocks as continuous income.
From 2011 to 2024, the monthly average expected return of domestic stocks was 0.09%, falling far short of the US's 0.53%. On the other hand, unexpected volatility was 10% higher than in the US. The period during which stock price upward trends continued was also shorter in Korea, averaging 2.3 months compared to the US's 3.1 months.
If people judge that stock prices could fall again at any time even after rising, the tendency to lock in profits becomes stronger than increasing consumption. In previous domestic studies, the probability of selling stocks that generated a profit was found to be more than twice as high as for loss-making stocks. This is higher than the 1.5 times shown in previous US studies.
The third reason is that profits generated from stocks move to real estate rather than consumption.
In a household panel analysis, it was estimated that when non-homeowning households generate 1 won in stock capital gains, real estate assets increase by 0.7 won. This does not mean that every non-homeowning household spends exactly 70% of their stock returns to buy a house, but it shows a strong correlation between stock capital gains and real estate acquisition.
The proportion of stock and bond sale proceeds among the own funds of home buyers in Seoul also rose from 4.9% in May 2025 to 8.9% in January 2026.
During the report's analysis period of 2011 to 2024, the monthly average expected return of housing was twice the level of stocks, and the volatility was only one-eighth. For non-homeowning households, it was a rational choice to save stock returns for a home purchase fund rather than consuming them.
Stocks acted not as an asset that increases consumption but as an intermediate ladder to cross over to real estate. As house prices rise, non-homeowning households reduce consumption and increase savings to raise the down payment and balance. The Bank of Korea explained this as 'forced savings' to achieve the goal of buying a home.
Consumption Shock Was Greater When Stock Prices Fell Than When They Rose
Recently, there are signs that the connection between the stock market and household consumption is strengthening. Domestic stockholders more than doubled from 6.12 million at the end of 2019 to 14.42 million at the end of 2025. The stock market participation of the youth and middle- and low-income classes has also expanded.
In 2025, households' stock capital gains, including funds, were estimated at 429 trillion won. This is 22 times the annual average of about 20 trillion won from 2011 to 2024. However, this amount is an estimate calculated by subtracting net purchases from the change in stock assets, and it includes unrealized valuation gains of held stocks as well as actual cashed-in profits.
If the market participation of the youth and middle- and low-income classes, who have a relatively large consumption response to increased assets, continues to expand, the wealth effect of domestic stocks could become larger than in the past.
The risks grow together as well. In the Bank of Korea's analysis, the consumption expansion effect following an increase in stock assets was 1.2% during an upturn, but the consumption reduction effect during a downturn was larger at 1.5%. Households view profits as temporary and carefully increase consumption when stock prices rise, but they show a tendency to reduce spending more quickly when prices fall.
In a situation where debt-leveraged investments, such as margin loans, have increased, a sudden drop in stock prices can simultaneously pressure households with asset reductions and principal and interest burdens. If the high-asset class reduces discretionary spending and the youth cut back on consumption to repay debts, the possibility of stock price declines leading to sluggish domestic demand also grows.
Between High-End and Cost-Effective, the Narrowing Middle Market
The two Bank of Korea reports do not directly explain the sales of Chanel and Daiso. Nor can it be seen that consumers buying luxury goods and those seeking cost-effective products are divided into two exact groups.
However, the numbers in the reports show why the consumer market is splitting into both sides. Assets and asset income are concentrated in the upper classes, while the burden of housing costs and savings for home purchases is piling up on the youth and non-homeowning households. The high-asset class has room for discretionary consumption remaining, but the low-asset class has to examine prices more meticulously even when purchasing essential goods.
In this structure, luxury goods with clear brand value and scarcity, and products with clear utility relative to price are each highly likely to be chosen. Conversely, the middle price range, which does not have as strong a brand as luxury goods nor is as cheap as cost-effective products, becomes difficult to be chosen by consumers.
Bank of Korea researchers suggested that household assets concentrated in real estate should be guided to productive sectors, and an investment environment must be created so that the stock market can become a stable asset formation channel for broader classes. The point is that there is a need to stabilize real estate prices to reduce the flow of stock capital gains heading back to real estate, and to increase households' incentives for long-term stock holding.
The simultaneous growth of the luxury and cost-effective markets may not be just a temporary fad created by a few brands. It is because the gap between those with assets and those without, the difference in income generated from assets, and the burden of housing costs and debt concentrated on the youth are pushing the consumer market in two directions.
If this structure does not change, it is highly likely that the high-end and cost-effective markets will grow, and the trend of the 'ambiguous premium' in between losing its footing will also continue for the time being.
※ The two BOK Issue Notes were written by researchers at the Bank of Korea's Research Department, and the reports state that their content reflects the personal views of the authors, not the official views of the Bank of Korea.
Company financial data, investment reports, and startup analysis — all in one place
Explore PitchdeckCurated news, every week — straight to your inbox
Every Friday · Unsubscribe anytime