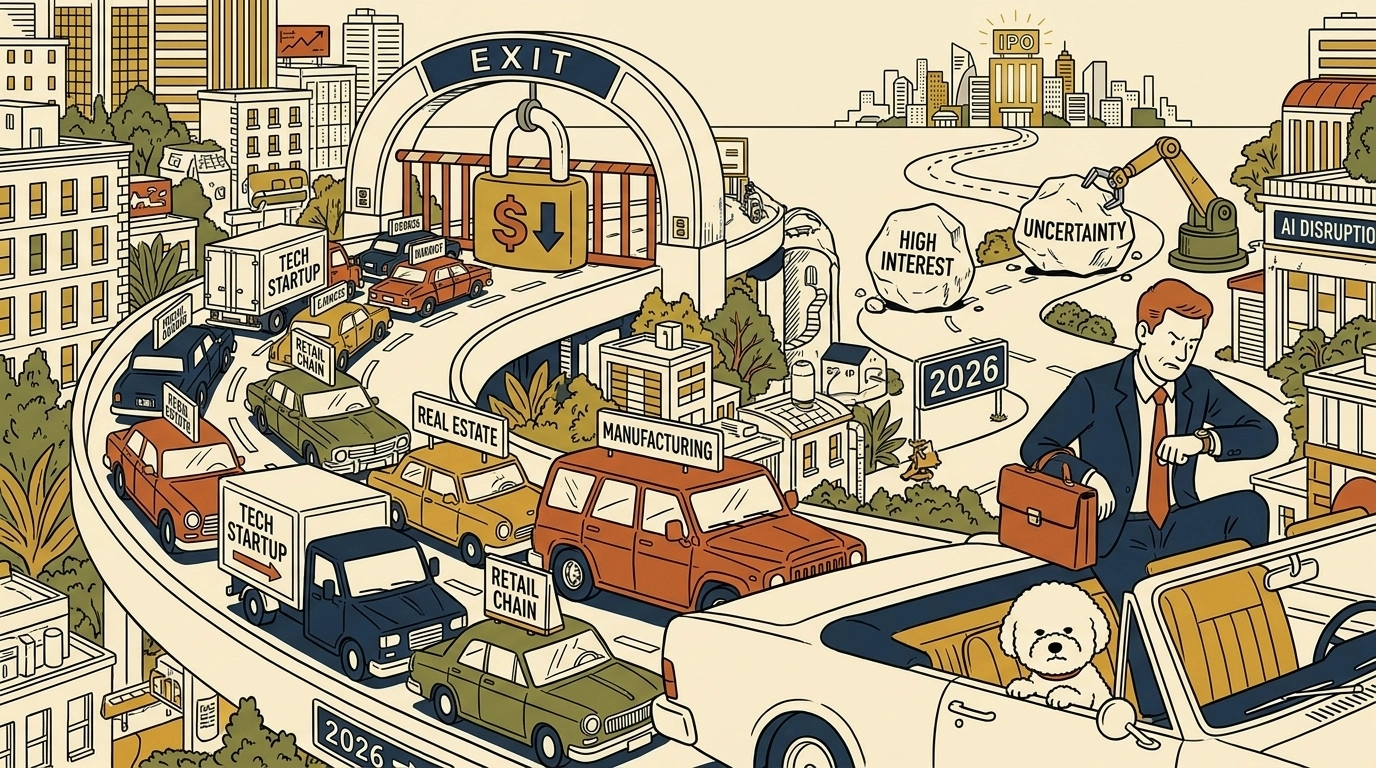
Number of Portfolio Companies Doubled in 10 Years... Average Holding Period of 7 Years
The number of companies global private equity funds have yet to sell or take public has swelled to 33,575. This is more than double the number from 10 years ago. Companies bought at high prices during the low-interest-rate era are now blocked from finding an exit by high interest rates, the spread of artificial intelligence, and economic uncertainty. However, selling them at a lower price would solidify losses and could shake investor confidence. This is why private equity funds are holding onto these companies and waiting it out.
According to a report by The New York Times citing data from the market research firm PitchBook, there were 33,575 unexited companies held by global private equity funds as of the end of June 2026. This is an increase of about 3.5% from 32,451 at the end of 2025. Ten years ago, the number was 15,923.
This does not mean that all unexited companies have failed to be sold or have fallen into financial distress. It also includes companies that have not yet entered a formal sale process or are being held longer for further growth. However, the simultaneous increase in the number of portfolio companies and their holding periods means that the capital circulation of private equity funds has slowed compared to the past. Private equity funds receive money from investors to acquire companies, improve their performance, and resell them to generate returns. Generally, the goal is to recover the investment by selling or going public within 5 to 7 years. If a company is not sold, money cannot be returned to investors, making it difficult to create new funds and acquire other companies.
Consulting firm Bain & Company estimated the valuation of unexited companies held by private equity funds at approximately $3.8 trillion. Among these, nearly 40% have been held for more than 5 years. In 2019, this figure was 29%. Companies sold in 2025 were also found to have been held by private equity funds for an average of about 7 years. The average holding period from 2010 to 2021 was 5 to 6 years.
Exit Value Increased, But Fewer Companies Sold
Looking only at 2025, it appears that private equity company sales have become active again. According to Bain, the exit transaction value for global buyout firms was $717 billion, up 47% from the previous year. However, a significant portion of this increase came from a few mega-deals. Seven company sales with transaction prices exceeding $10 billion totaled $155 billion, accounting for 22% of the total exit transaction value. The value of transactions under $10 billion also increased by 34%, but the total number of sales actually decreased by 2% to 1,570. While the overall transaction volume increased as a few large companies were sold at high prices, this did not mean that the numerous companies held by private equity funds were sold evenly across the board.
Moving into 2026, the M&A market has shrunk again. According to PitchBook's 'Q2 2026 US PE Breakdown,' the exit transaction value for US private equity funds in the second quarter was $102.6 billion. This was a 46.3% decrease from $191.1 billion in the first quarter. Transactions where private equity funds sell portfolio companies to other private equity funds also decreased by about 40% compared to the previous quarter. Private equity funds have long been a major buyer for other private equity funds, but as the entire industry struggles with capital recovery, even this avenue has narrowed.
According to Reuters Breakingviews calculations, for the five years prior to the COVID-19 pandemic, the volume of initial public offerings (IPOs) and sales to corporate buyers equated to about one-third of the total assets held by private equity funds each year. Since 2020, that ratio has fallen below an average of one-fifth. While the number of companies held by private equity funds has grown rapidly, the market to absorb them has not expanded commensurately.
Scope | Indicator | Figure | Reference |
|---|---|---|---|
Global | Unexited Portfolio Companies | 33,575 | End of June 2026 |
Global | Unexited Companies at End of 2025 | 32,451 | Increase of 1,124 in 6 months |
Global | Unexited Companies 10 Years Ago | 15,923 | Currently about 2.1 times that of the past |
(Source: Compiled from NYT, PitchBook, WSJ, etc.)
IPOs Increased, But Still a Narrow Door
It is positive that the IPO market has partially revived. In 2025, IPOs by global private equity-backed companies increased by 36% from the previous year. However, this was an increase compared to a very sluggish prior year. Bain evaluated that IPOs still remained a secondary exit avenue for private equity funds.
The preparation process for an IPO is complex, and corporate valuations can vary greatly depending on stock market conditions. It is also a realistic option only for a select few companies equipped with the scale, performance, and market recognition. This is why management firms cannot easily opt for an IPO even when the stock market is rising.
According to Dealogic data, there were 70 private equity-backed companies that went public since 2022. This is a stark contrast to the more than 400 companies between 2017 and 2021.
Even a 5% Discount Sale Shakes Confidence
Valuation methods also play a role in private equity funds continuing to hold onto companies instead of selling them. In an April 2026 webcast survey by the Institutional Limited Partners Association cited by Bain, a majority of investors responded that their trust in a management firm begins to weaken if a company's actual sale price is more than 5% lower than its most recent book value. 5% is not an official rule. Since it is a survey targeting webcast participants, it is difficult to see it as a direct representation of all investors' thoughts. However, it does show the burden private equity management firms feel when selling companies at a lower price.
Selling a company with a book value of 100 billion won for 94 billion won solidifies a loss. Investors might suspect that the book values of other portfolio companies have also been set higher than reality. This also works disadvantageously when the management firm creates its next fund. From the management firm's perspective, it may be better to hold onto the company longer and wait for performance to catch up to the book value, rather than selling it cheaply and cementing a loss. The problem is that while waiting, interest expenses continue to accrue, and the money to be returned to investors remains tied up.
In the same survey, about 1 in 5 investors responded that they are reducing their proportion of buyout investments due to concerns over delayed capital recovery and long-term returns. Private equity funds are buying time by extending loan maturities or transferring companies held by existing funds to new funds. This is known as a 'continuation fund.'
In 2025, the transaction volume of general partner-led continuation funds grew by 62%. However, its share of the total private equity exit transaction value is less than 10%. It can alleviate immediate funding difficulties, but it is not a fundamental solution to dealing with the backlog of companies.
AI Has Shaken Software Company Valuations
The spread of artificial intelligence has made selling software companies even more difficult. Boasting steady subscription revenues and high profit margins, software companies were popular with private equity funds during the low-interest-rate era. However, as concerns grow that generative AI could replace the functions of existing software, it has become difficult to evaluate the future earnings of these companies.
According to Bain, technology buyout transaction values fell by 70% between the fourth quarter of 2025 and the first quarter of 2026. The book value of software companies held by private equity funds also dropped by an average of about 8% in the first quarter of 2026. US companies fell by 8.9% and European companies by 4.2%. The decline was smaller than that of publicly traded software companies. It could be that unlisted software companies actually absorbed less of a shock, but it could also be because the book values of unlisted companies are adjusting more slowly than stock prices.
However, AI cannot be entirely blamed as the reason private equity funds are unable to sell companies. AI is closer to being a factor that amplified uncertainty for software companies in a market already blocked by high interest rates, high acquisition prices, and a lack of buyers.
Not All Book Values Are Inflated
It also cannot be concluded that the book values of private equity funds are all set higher than reality. According to an MSCI analysis cited by Bain, more than 75% of global buyout companies sold between 2021 and 2025 were sold at prices higher than their book values before the sales went into full swing. Here, the comparison was made against the book value not from the quarter immediately preceding the sale, but from the quarter before that. This is because right before a sale, prices confirmed during the bidding and due diligence processes are often already reflected in the books.
However, these statistics only cover companies that were successfully sold. It does not mean that the book values are appropriate for companies that could not be put on the market or failed to find buyers.
Cash Returned to Investors at Financial Crisis Levels
An increase in sale transaction value does not mean cash was immediately returned to investors. According to Bain, distributions returned to investors by private equity funds in 2025 amounted to only 14% of net asset value. This is a level rarely seen since the 2008-2009 global financial crisis. This ratio falling below 15% for four consecutive years marks the longest record in the industry.
Returns also fell short of the stock market. According to MSCI, the annualized return of US private equity funds from July 2022 to March 2026 was 6.4%. During the same period, the Standard & Poor's 500 index recorded 15.2%, and the Nasdaq index recorded 19.3%.
5% Growth Was Enough in the Past, But Now 12% Is Needed
Bain explains the changed private equity market with the phrase '12 is the new 5.'
Ten years ago, it was possible to borrow about half of the acquisition cost at low interest rates. There were also many cases where the price applied when selling a company was significantly higher than the price applied when buying it. Even without vastly improving the company's performance, returns could be generated with the help of leverage and rising market prices.
In an example presented by Bain, it was assumed that in 2015, a private equity fund could buy a company at a price 10 times its earnings and sell it 5 years later at 12.5 times. The borrowing rate was about 6%. In a 2025-style transaction, it was assumed that a company is bought at 14 times its earnings, but the sale price 5 years later is 15 times. While buying at a higher price from the start, the margin of price increase that can be received upon resale has shrunk. The borrowing rate has also risen to about 8%.
Simply put, in the past, cheap interest and rising sale prices jointly generated returns. Now, one has to buy companies at expensive prices and bear higher interest rates, while it is also difficult to expect prices to rise significantly upon resale.
Bain analyzed that in the past, even if a company's operating profit before interest, taxes, etc., grew by 5% annually, 2.5 times the investment could be recovered over 5 years; however, to generate the same return now, it must grow by 10 to 12% annually.
Ultimately, the backlog of 33,575 companies held by private equity funds is not simply a matter of the transaction market freezing temporarily. It is a signal that the past investment methods, which relied on low interest rates, leverage, and rising sale prices, are no longer working as they used to. Private equity funds must either boost the performance of their portfolio companies and wait until they get the desired price, or lower the price to sell and return cash to investors. Neither is an easy choice. Going forward, the competitiveness of private equity funds is highly likely to be determined by how much actual cash is returned to investors rather than the return rates written on the books.
Company financial data, investment reports, and startup analysis — all in one place
Explore PitchdeckCurated news, every week — straight to your inbox
Every Friday · Unsubscribe anytime