
Carriesoft invests KRW 10 billion from paid-in capital increase to secure a 50.36% stake in Studio Episode
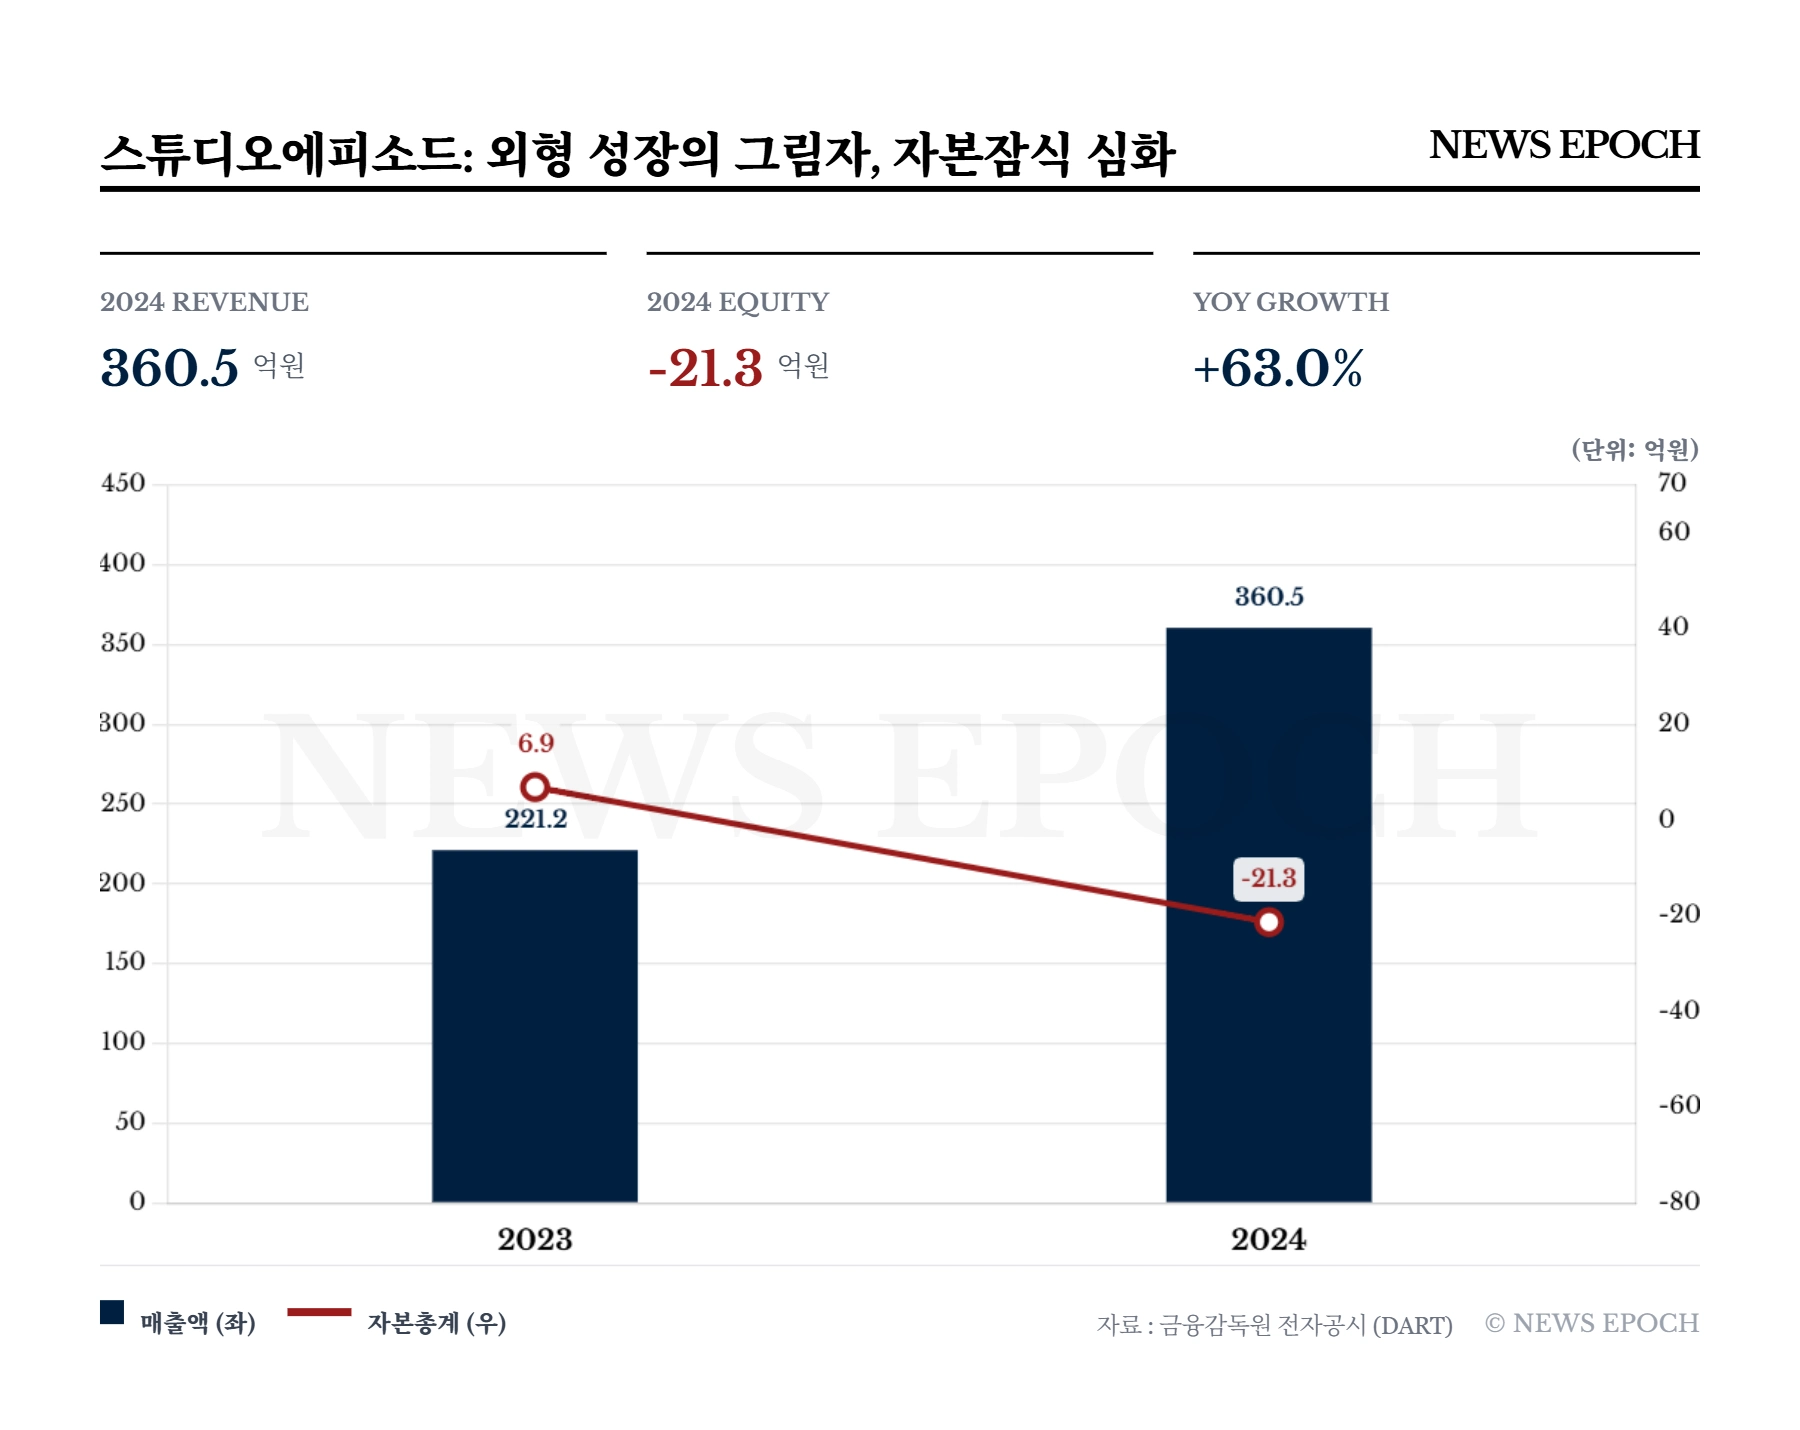
Studio Episode's revenue grew 63% YoY, but is in a state of 'capital impairment' due to accumulated deficits
Raised funds by attracting investors like Netmarble and Dotree... Need to check financing conditions such as put options and borrowings
Studio Episode, which operates the YouTube channels of prominent stars whose names alone carry weight—such as Choo Sung-hoon, Lee Min-jung, Yano Shiho, and Jeon Somi, led by 'Today's Joo Woo-jae'—has been incorporated as a subsidiary of KOSDAQ-listed company Carriesoft. As Carriesoft, familiar for its kids' content, embraces the channels of trending celebrities like Joo Woo-jae and Choo Sung-hoon all at once, the attention of the entertainment industry is focusing on it.
However, a close analysis of both companies' financial statements reveals that this merger and acquisition (M&A) is closer to a 'survival-driven combination' to offset each other's financial flaws rather than an 'investment' for synergy creation. We examined the reality pointed to by the numbers behind this meeting of a listed company facing a revenue cliff and a large but undercapitalized unlisted company.
'KRW 36 billion in Revenue' Studio Episode, in Reality 'Complete Capital Impairment'
Studio Episode, the core of this deal, recorded KRW 36 billion in revenue as of 2024, growing 63% compared to the previous year (KRW 22.1 billion). Its top-line growth was driven by a lineup of YouTube channels with massive traffic—led by 'Today's Joo Woo-jae', along with 'Choo Sung-hoon', 'Lee Min-jung', 'Jo Seung-yeon's Exploration Life', 'Yano Shiho', 'Kim Ho-young', 'Hi Seulgi (Red Velvet Seulgi)', and 'Jeon Somi'—and the commerce business linked to them.
What is noteworthy is its financial soundness. During the process of external expansion, selling, general, and administrative (SG&A) expenses surged, resulting in an operating loss of KRW 2.3 billion in 2024, and deficits accumulated due to sustained net losses. As a result, its total equity stood at negative KRW 2.13 billion as of the end of 2024, placing it in a state of 'complete capital impairment' where its paid-in capital (KRW 110 million) has been fully exhausted and liabilities exceed assets. For Studio Episode, at a point where its independent survival had reached its limit, selling its management rights to Carriesoft, a listed company with liquidity, provided an opportunity to resolve its capital impairment and normalize its finances.
Carriesoft: 10-fold Expansion in Consolidated Revenue and Listing Maintenance Strategy
From the perspective of the acquirer, Carriesoft, this deal was not a simple investment but a strategic move for 'survival'. Carriesoft's main business, the kids' content business, is showing a clear downward trend.
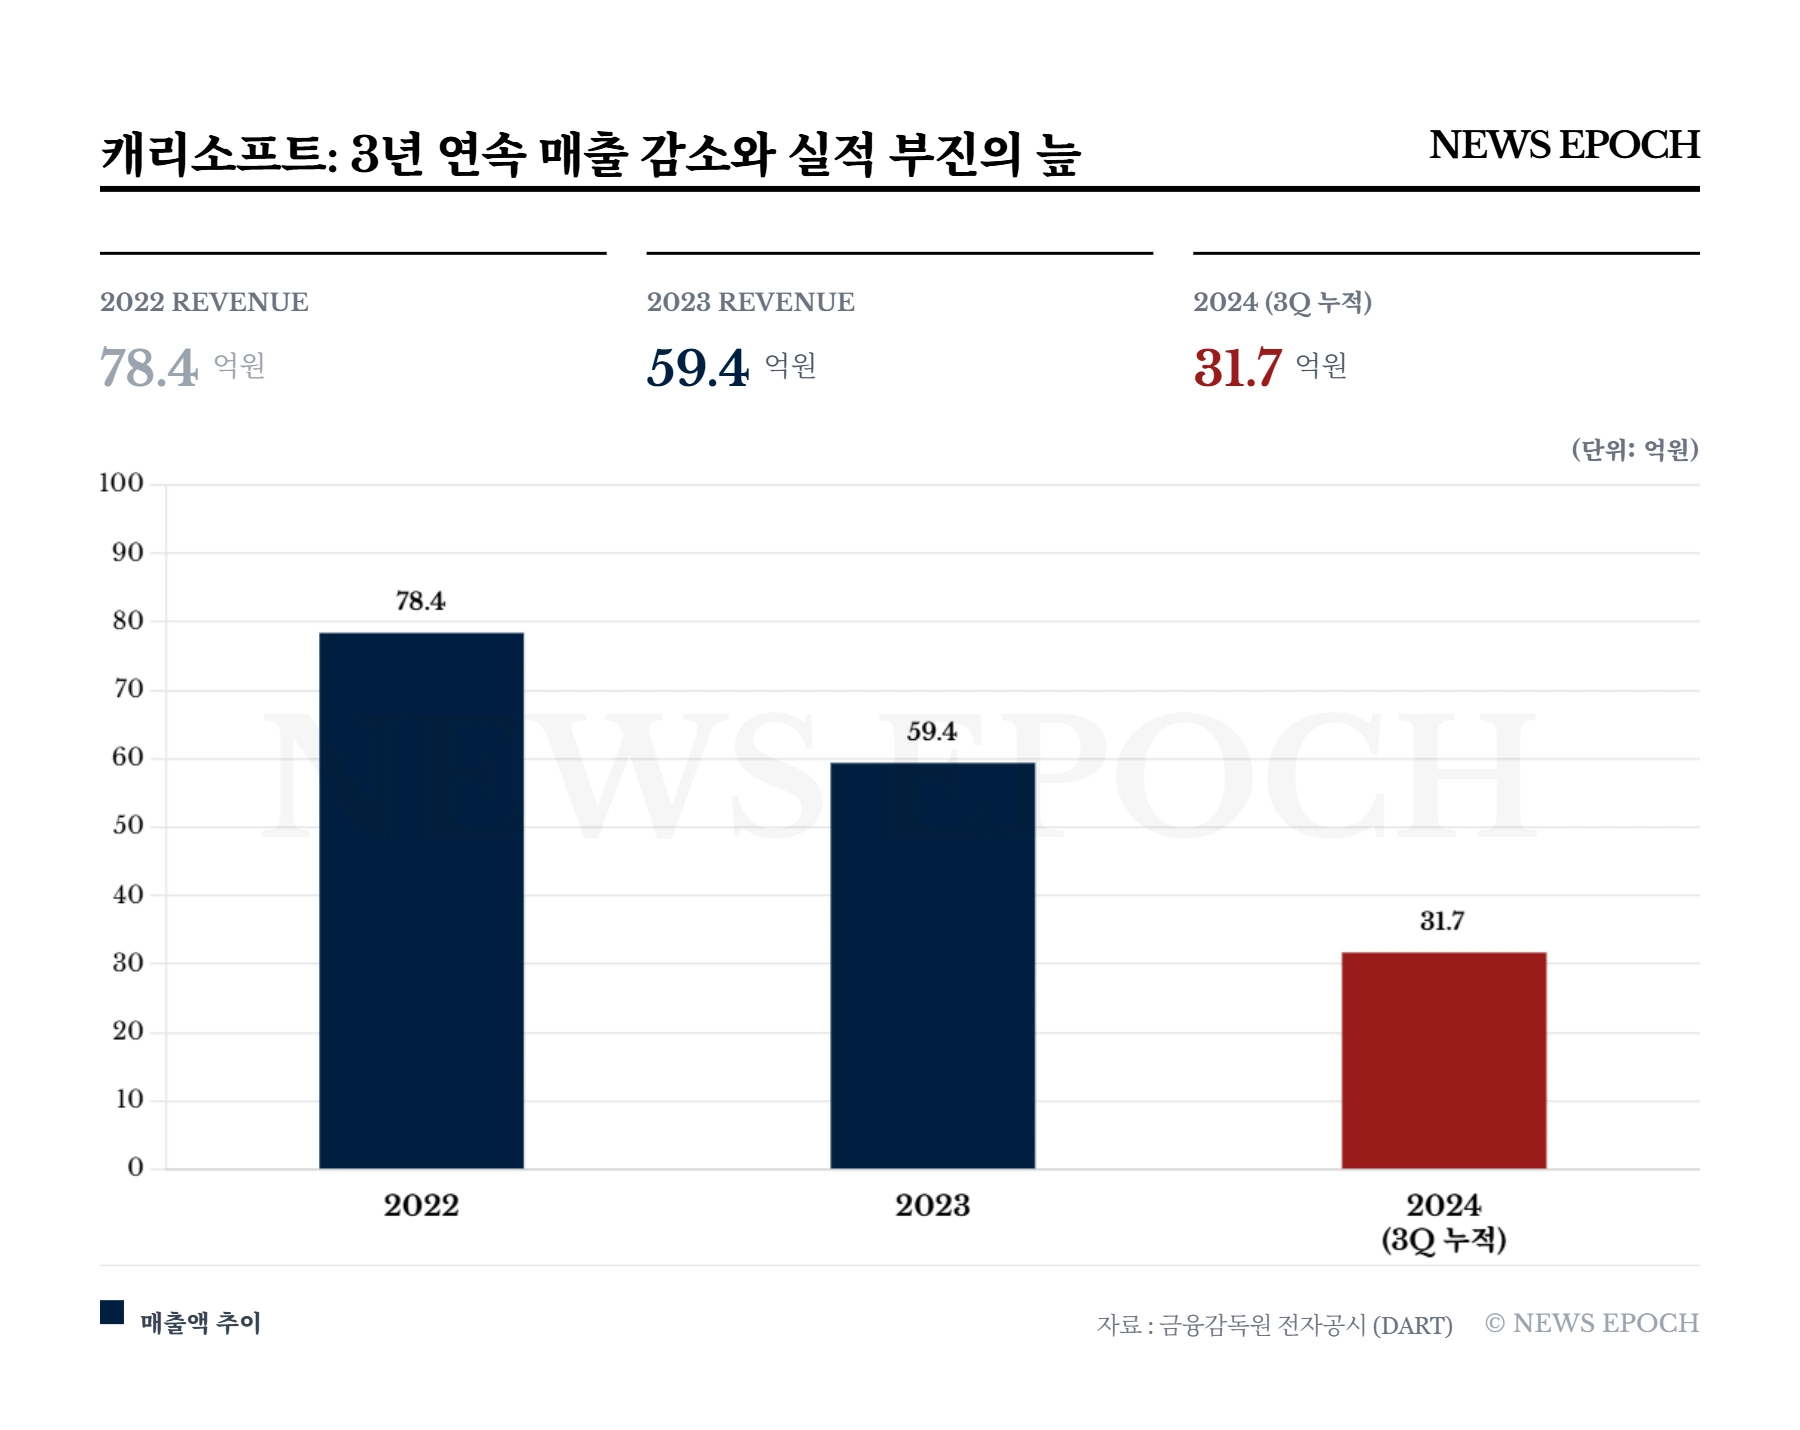
According to disclosures, Carriesoft's revenue decreased from KRW 7.8 billion in 2022 to KRW 5.9 billion in 2023, and shrank to KRW 3.1 billion on a cumulative basis up to the third quarter of 2024. This is a 'revenue cliff' situation where its external size has been halved in just two years. More painful than the consecutive operating deficits for five years was the loss of growth engines.
In this crisis, the acquisition of Studio Episode, with an annual revenue of KRW 36 billion, is interpreted as a drastic measure and the only breakthrough. Through an unusual combination where the acquired company (Studio Episode) has a revenue more than 10 times larger than the acquiring entity (Carriesoft), Carriesoft will instantly inflate its revenue scale to the KRW 40 billion range on its consolidated financial statements. This is analyzed as the result of a strategic decision to maintain market dominance as a KOSDAQ-listed company and defend its corporate value.
Of KRW 28 billion in Raised Funds, KRW 19 billion Injected into Acquiring 'Deficit Companies'
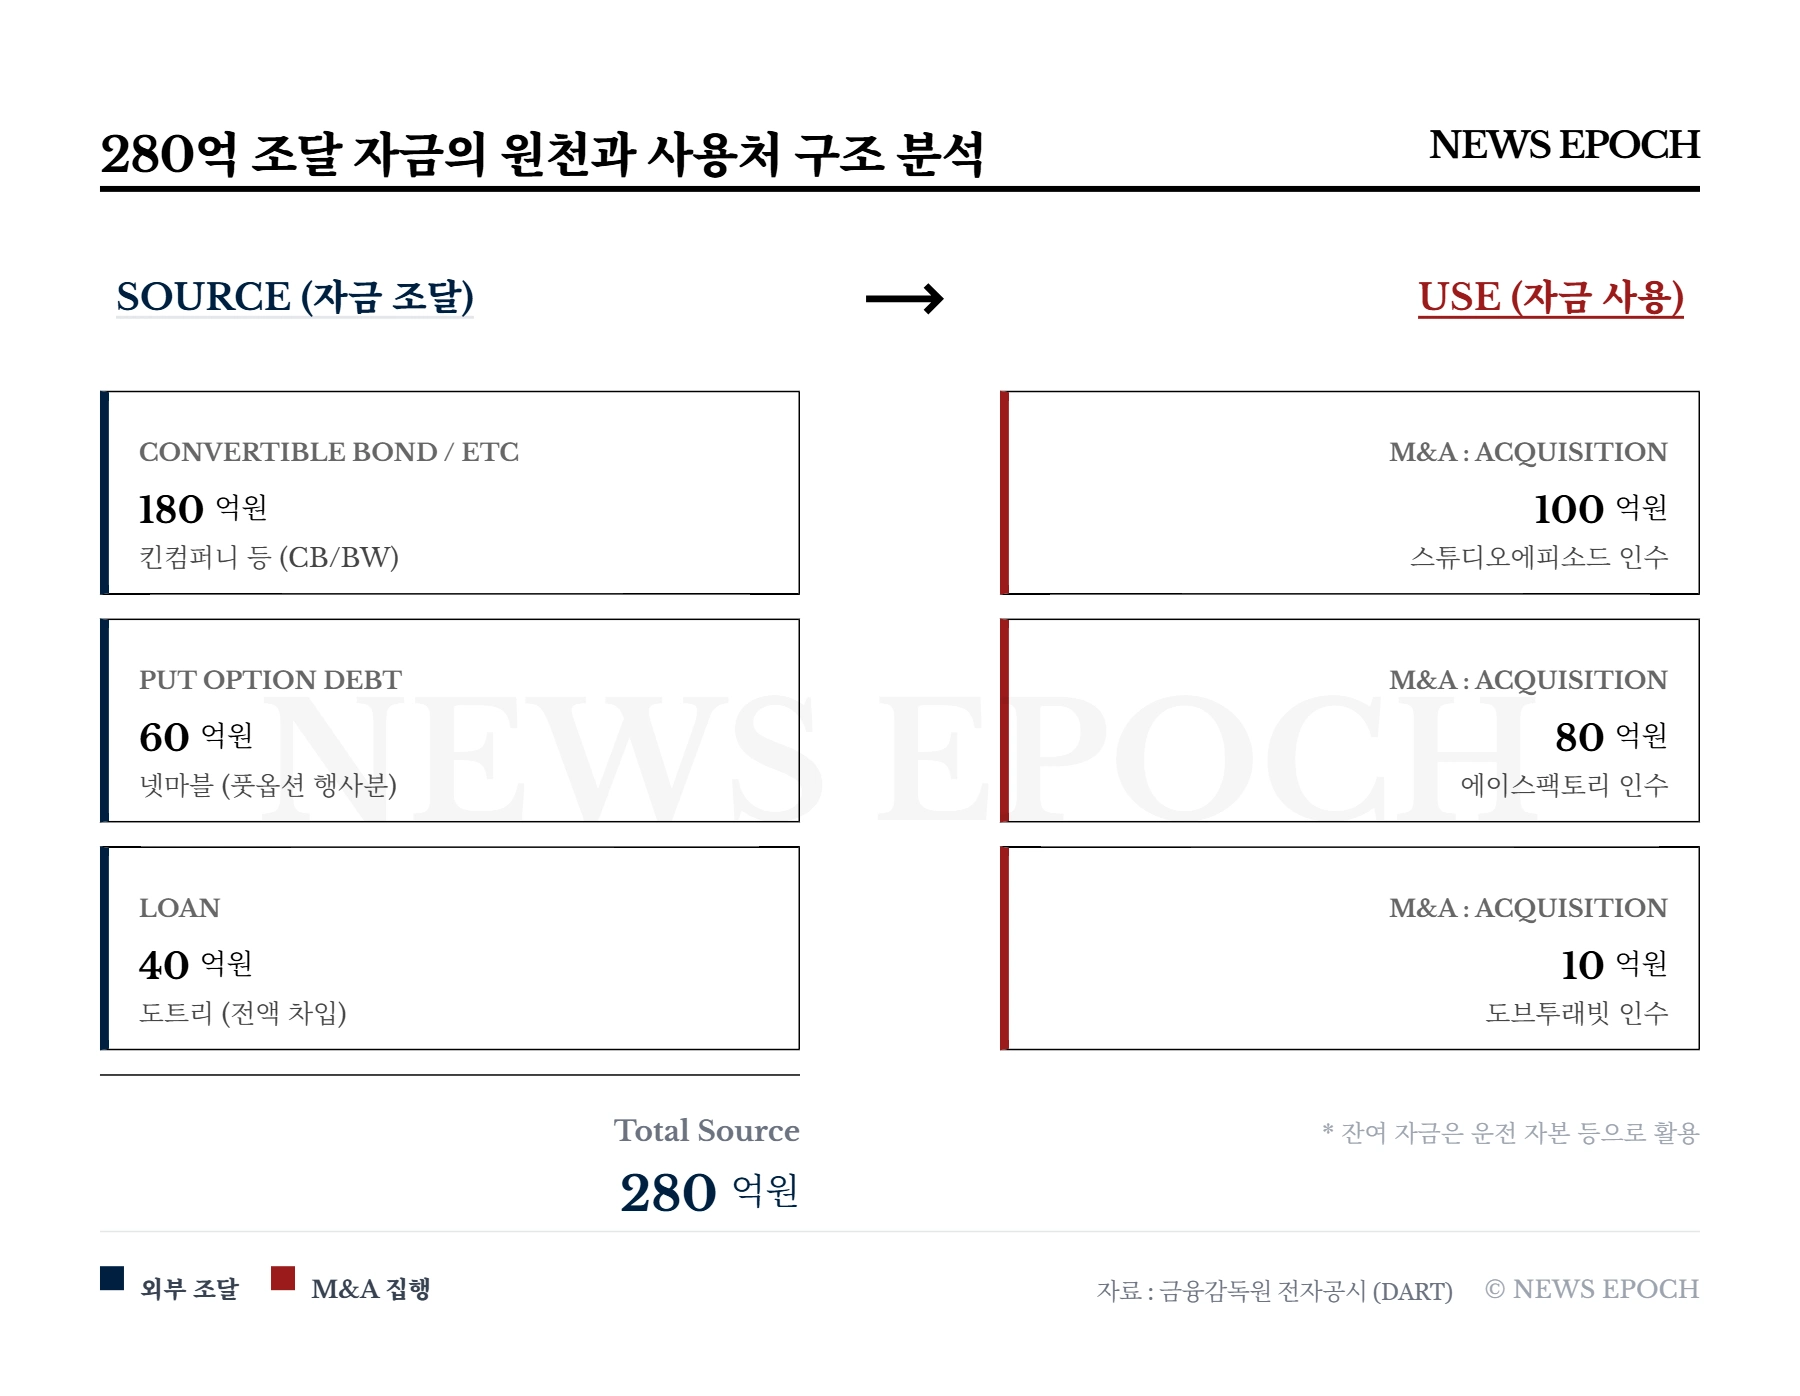
This acquisition was made based on approximately KRW 28 billion in funds raised by Carriesoft through a paid-in capital increase. However, a close look at the use of funds and financing conditions calls for caution regarding liquidity management and overhang issues.
First, the fund depletion rate is steep. Carriesoft is injecting ▲approximately KRW 10 billion into the acquisition of Studio Episode and ▲ACE FACTORY acquisition for KRW 8 billion. Adding to this the marketing firm ▲Dovetorabbit's convertible bond (CB) acquisition (KRW 1 billion), a total of KRW 19 billion, which is about 70% of the raised funds, is being spent in just two months. The remaining cash is expected to be tightly managed for resolving capital impairment risks and as operating funds. Considering additional strategic investments, the actual available cash capacity shrinks further. In fact, Carriesoft also announced an investment plan in comprehensive entertainment company Team Hope.
The composition and conditions of the investors who provided the large-scale funds are also points to watch closely. Netmarble F&C (KRW 6 billion investment), which has become the second-largest shareholder of Carriesoft (11.3% stake), handed over (sold) ACE FACTORY to Carriesoft for KRW 8 billion, effectively taking a structure that recovers more cash than its KRW 6 billion investment. In addition, it established a 'put option' for the remaining stake, securing a safety mechanism to get the principal back depending on future circumstances.
Another investor, Dotree (KRW 4 billion investment), disclosed that it prepared the entire investment amount through external borrowing (loans) without using its own capital. As the investment (leverage) was effectively made with 100% debt, the possibility cannot be ruled out that a large-scale sell-off (overhang) for loan repayment will pour out depending on the stock price trend one year later when the lock-up is released.
Carriesoft emphasized future value, stating that through this acquisition, it has completed a 'comprehensive content value chain' encompassing infants to adults. However, the reality shown by the financial statements is grim. This M&A, where Carriesoft's 'sluggish revenue' and Studio Episode's 'capital impairment' intersect, is interpreted as the result of a fierce 'survival equation' to fill each other's financial deficiencies beyond simple external expansion. The success or failure of this 'survival equation' is expected to be determined one year later, when the lock-up release coincides with the possibility of investors exercising put options and the maturity of borrowings.
Company financial data, investment reports, and startup analysis — all in one place
Explore PitchdeckCurated news, every week — straight to your inbox
Every Friday · Unsubscribe anytime