
Despite the overvaluation controversy of a 100x PER, Shinsegae opened its wallet to secure a 'Japanese distribution network'
Naver Snow executes a 'survival exit' by selling its lucrative subsidiary amidst accumulated deficits
In the second year of acquisition, sales increased by 40%, but the profit margin is in the 1% range... Concerns of an 'all flash, no substance' acquisition arise
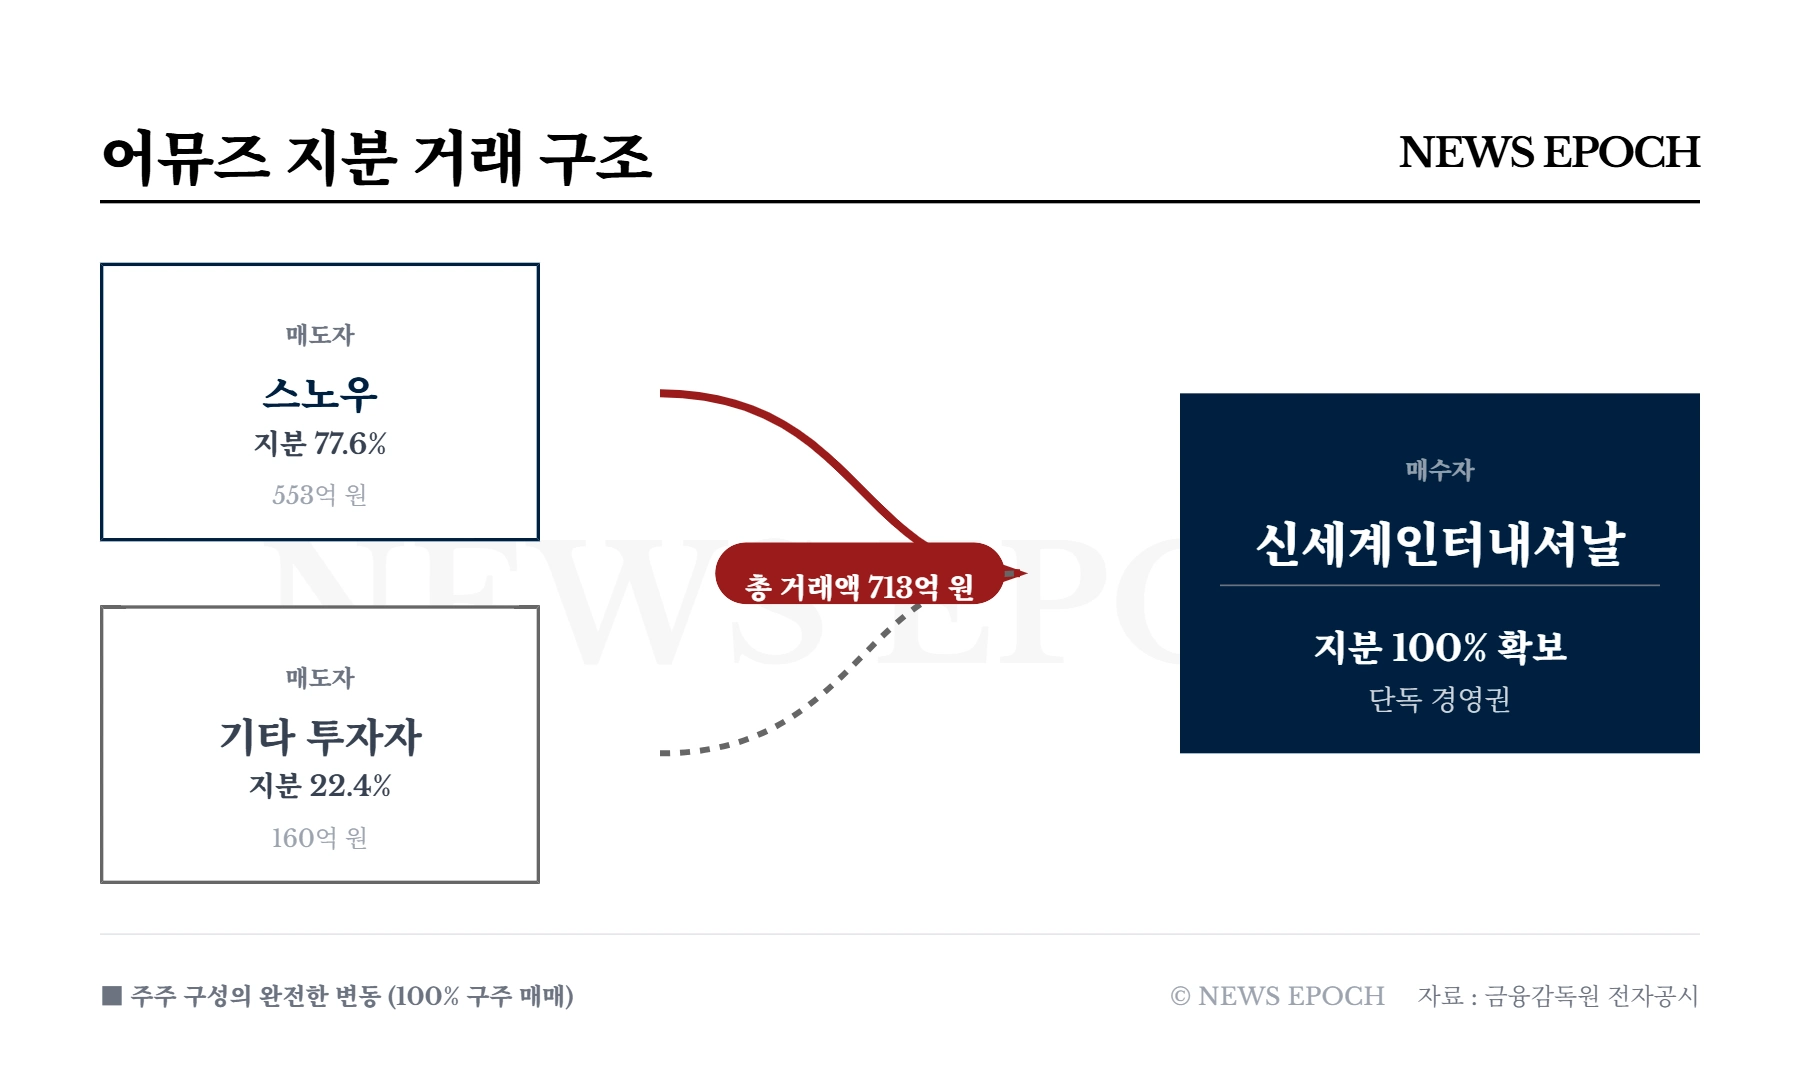
It has been 1 year and 5 months since Shinsegae International embraced the beauty brand 'Amuse (AMUSE)'. In August 2024, Shinsegae signed a share purchase agreement (SPA) to acquire a 100% stake in Amuse for 71.3 billion won. The market packaged this deal as an 'acquisition of a startup by a large conglomerate,' but the reality indicated by the financial statements is different. This is the result of Naver (Snow)'s urgent need to 'secure cash' to cover the parent company's deficit coinciding with Shinsegae's 'purchase of Japanese entry rights' after hitting the limits of the domestic market. Ahead of the 2025 audit report to be released this coming March, the appropriateness of the 71.3 billion won valuation was analyzed using financial data.
Snow's Exit: Profit Realization or Financial Structure Improvement?
For Snow, the former parent company of Amuse, this sale was an inevitable choice from a financial perspective. Although it secured vast user data with its globally popular camera app, Snow itself had failed to find a solid profit model and had been recording operating losses for years. Within the group, Amuse was the only subsidiary yielding visible results, so for the financial soundness of the parent company, selling the most valuable asset to secure cash was the most efficient plan.
In fact, looking at the structure of the deal reveals this financial judgment. It is understood that Snow primarily injected the 55.3 billion won in cash secured from the sale of Amuse into operating funds for its main business and covering accumulated deficits, rather than expanding into new businesses. While CJ Olive Young and Mirae Asset Venture Investment, who sold their shares together, had a financial investment recovery where they took profits compared to their principal investment, the dominant interpretation is that the sale by the largest shareholder, Snow, was a strategic judgment to secure immediate liquidity and improve its financial structure.
What Shinsegae Bought Was Not Cosmetics, But a 'Japanese Distribution Network'
Shinsegae International paid 71.3 billion won, betting on the turnaround potential of Amuse, which was in a deficit until 2023, and its potential in the Japanese market. Although it was a bold investment at the time, it is difficult to avoid the 'overvaluation controversy' when factoring in the confirmed results of 2024. This is because Amuse's annual net profit in 2024 was only about 700 million won. Substituting this into the acquisition price (71.3 billion won), the price-to-earnings ratio (PER) reaches approximately 102 times. This figure far exceeds the level expected in a typical corporate acquisition. Ultimately, rather than immediate profit generation, Shinsegae purchased the 'Japanese market distribution network,' which is difficult to secure in a short period by starting from scratch. It is an 'upfront investment of opportunity cost,' substituting the more than 5 years of time and marketing expenses required to establish its own brand in Japan with 71.3 billion won.
Sales of 52 Billion vs. Marketing Costs of 9 Billion... Profitability Concerns Amidst Outward Growth
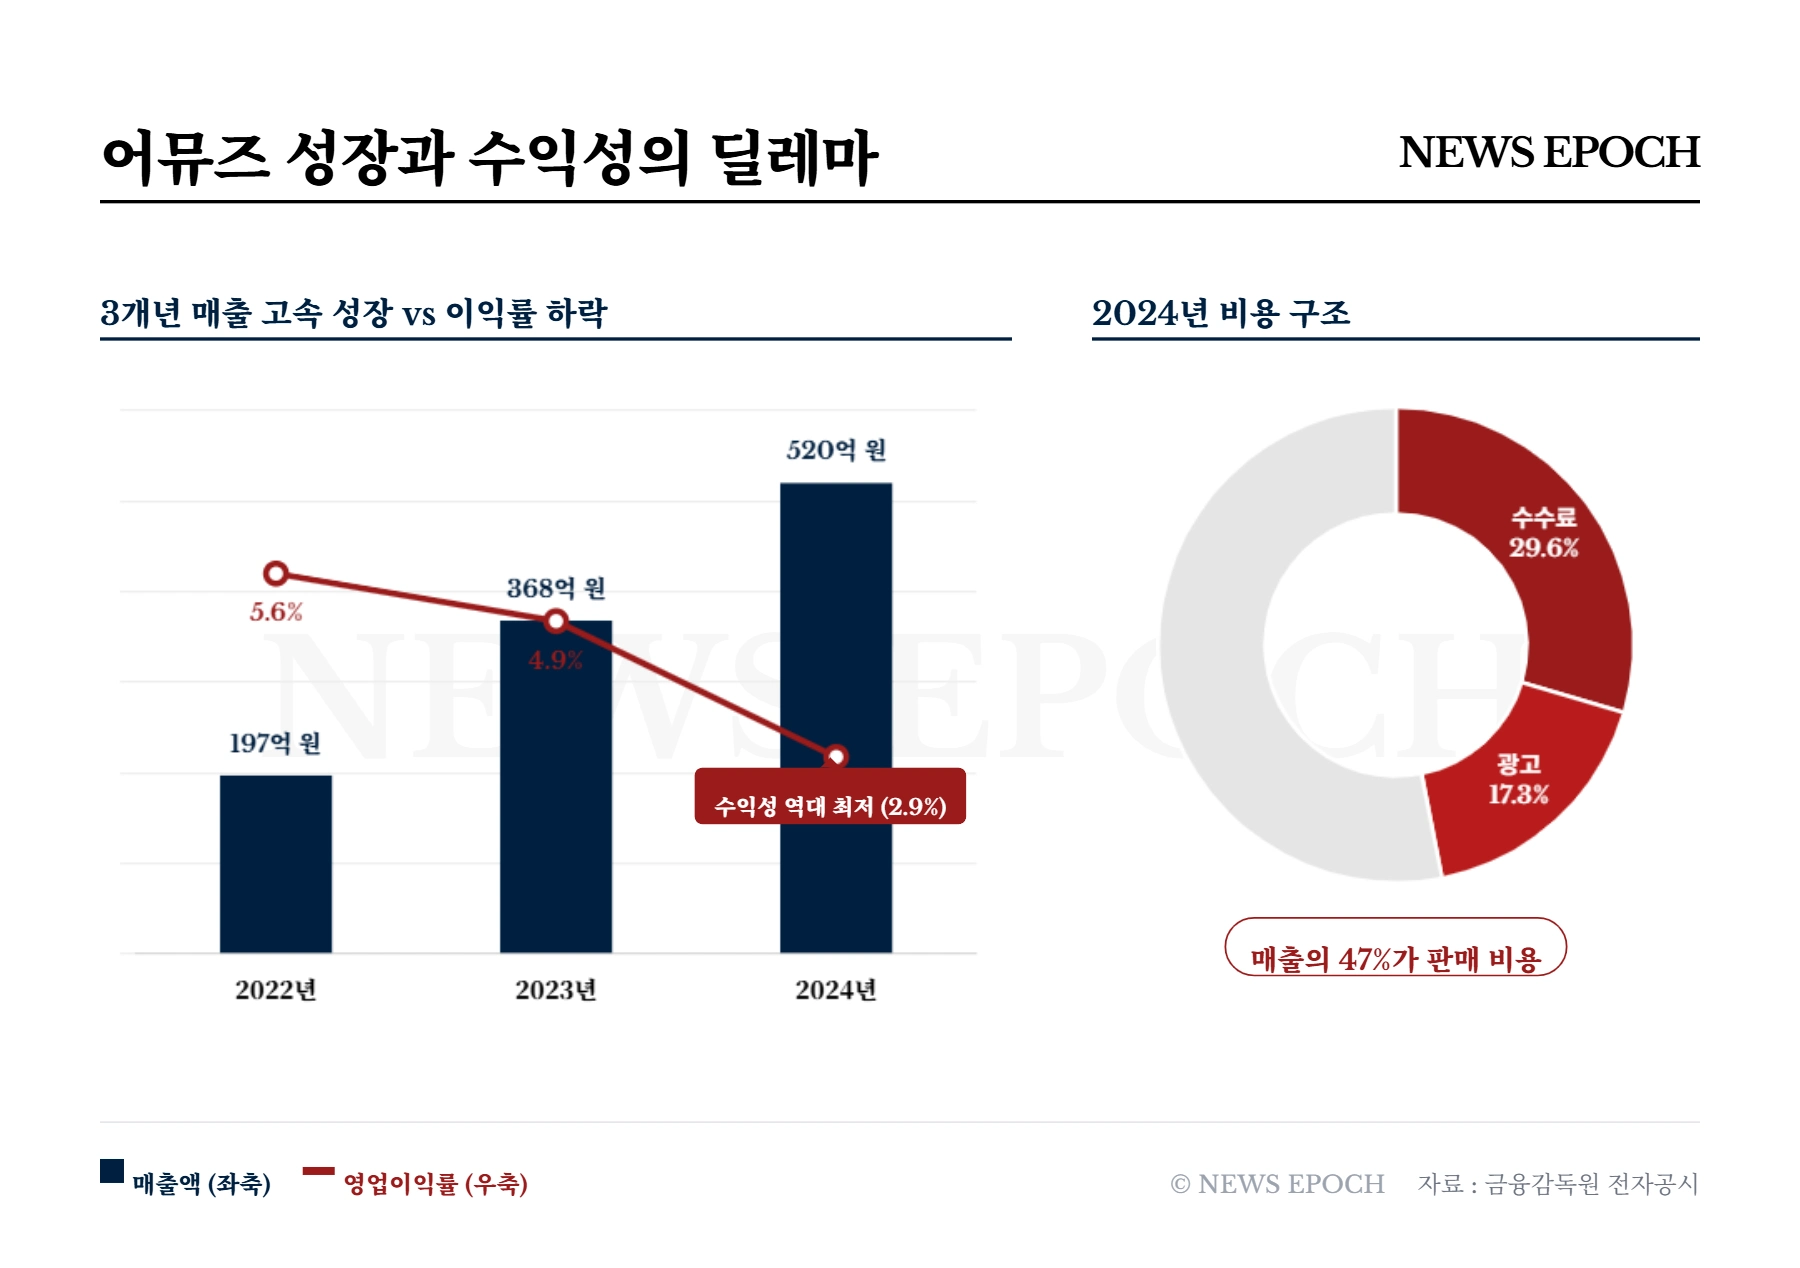
In the second year of acquisition, Shinsegae's outward expansion strategy was spot on. Amuse's sales in 2024 recorded 52 billion won, growing more than 41% compared to the previous year (36.7 billion won). However, unlike the steep sales growth, profitability indicators worsened. Although sales increased, operating profit was only 1.5 billion won, and the operating profit margin dropped from 4.9% in 2023 to 2.9% in 2024. The causes lie in the defense costs for the Japanese market and platform fees. According to the audit report, advertising and promotional expenses in 2024 surged by over 60% year-on-year to 9 billion won, and the fee expenses paid to open markets and others reached 15.4 billion won. It is a structure where nearly half of the sales are spent on advertising and fees. Ultimately, while the sales volume has grown, it has fallen into a profitability dilemma where the actual margin rate drops as the cost burden intensifies.
2026, The Watershed That Will Determine the Success or Failure of the Acquisition
This deal, executed a year and a half ago, is also an important management test for Shinsegae International's General CEO Lee Seung-min, who led the acquisition of Amuse. For him, who rose to the group CEO position in recognition of the achievements of the Amuse acquisition, 2026 is the year he must prove his management capabilities with numbers. This is because while Naver and CJ finished their roles in the initial brand building stage and divested their stakes, Shinsegae has now entered a full-fledged profit generation stage. The key depends on whether it can achieve marketing cost efficiency while maintaining its current market dominance in Japan. If it fails to achieve visible improvement in operating profit again this year, the large-scale investment of 71.3 billion won could become a factor that hinders the group's financial efficiency. The 2025 audit report to be released this March is expected to be the first indicator to gauge whether Shinsegae's bet at the time was a stepping stone for mid-to-long-term growth or if it will remain a cost burden.
Company financial data, investment reports, and startup analysis — all in one place
Explore PitchdeckCurated news, every week — straight to your inbox
Every Friday · Unsubscribe anytime