Established in the second half of 2021 as a subsidiary of the comprehensive content company BY4M Studio, the growth trajectory of Natureloud is fierce. Backed by its parent company's digital marketing and entertainment infrastructure, it has taken differentiated steps since the early stages of its business.
In 2023, the company grew in size through the merger and acquisition (M&A) of WithVP Co., Ltd., which operates media commerce and the unmanned photo studio 'Geumeumdal Self Studio', and successfully launched the premium dessert brand 'Yukimochi', achieving the remarkable feat of expanding to 14 direct stores in just 6 months. As a result, its consolidated revenue, which was about 26.6 billion won in 2023, drew an explosive upward curve to about 39.3 billion won in 2024, and a whopping 90.1 billion won in 2025. However, what truly captures the market's attention is the 'unconventional financial technique' hidden behind this brilliant performance.
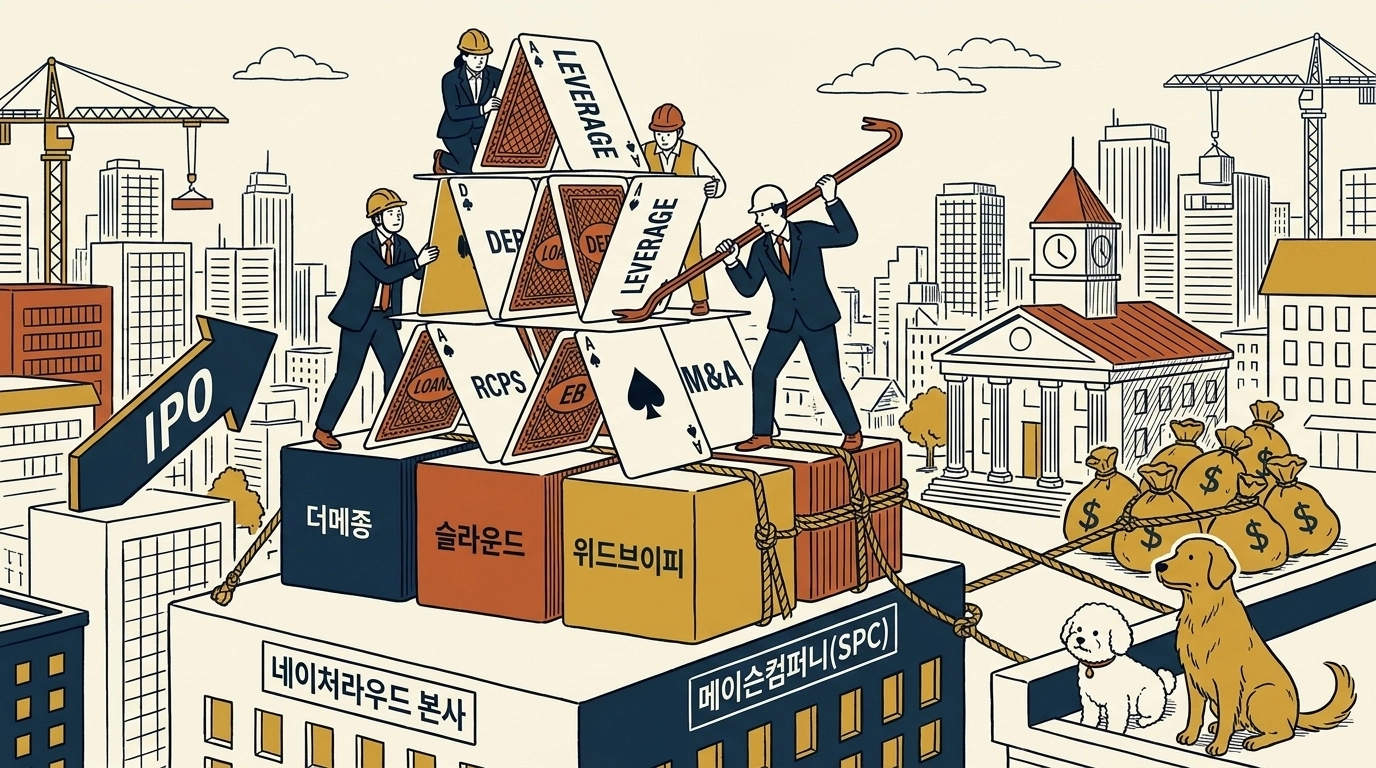
This is an unconventional financial technique rarely seen in the startup ecosystem, in which BY4M Studio's subsidiary Natureloud employed a 'Full Leverage' strategy strictly utilizing external funds and borrowings as a lever in the process of acquiring the lifestyle companies 'The Maison Co., Ltd.' and 'Slound Co., Ltd.' Behind this structured finance, which effectively accomplished an M&A worth in the 60 billion won range by fully mobilizing investments and debt without any of its own cash surplus, lies a powerful triple- and quadruple-layered put option (right to claim the purchase of shares) contract that could shake up the entire group if listing (IPO) or growth fails.
A Typical 'LBO' Completed with Debt and External Funds… Establishing a 5-Stage Vertical Structure
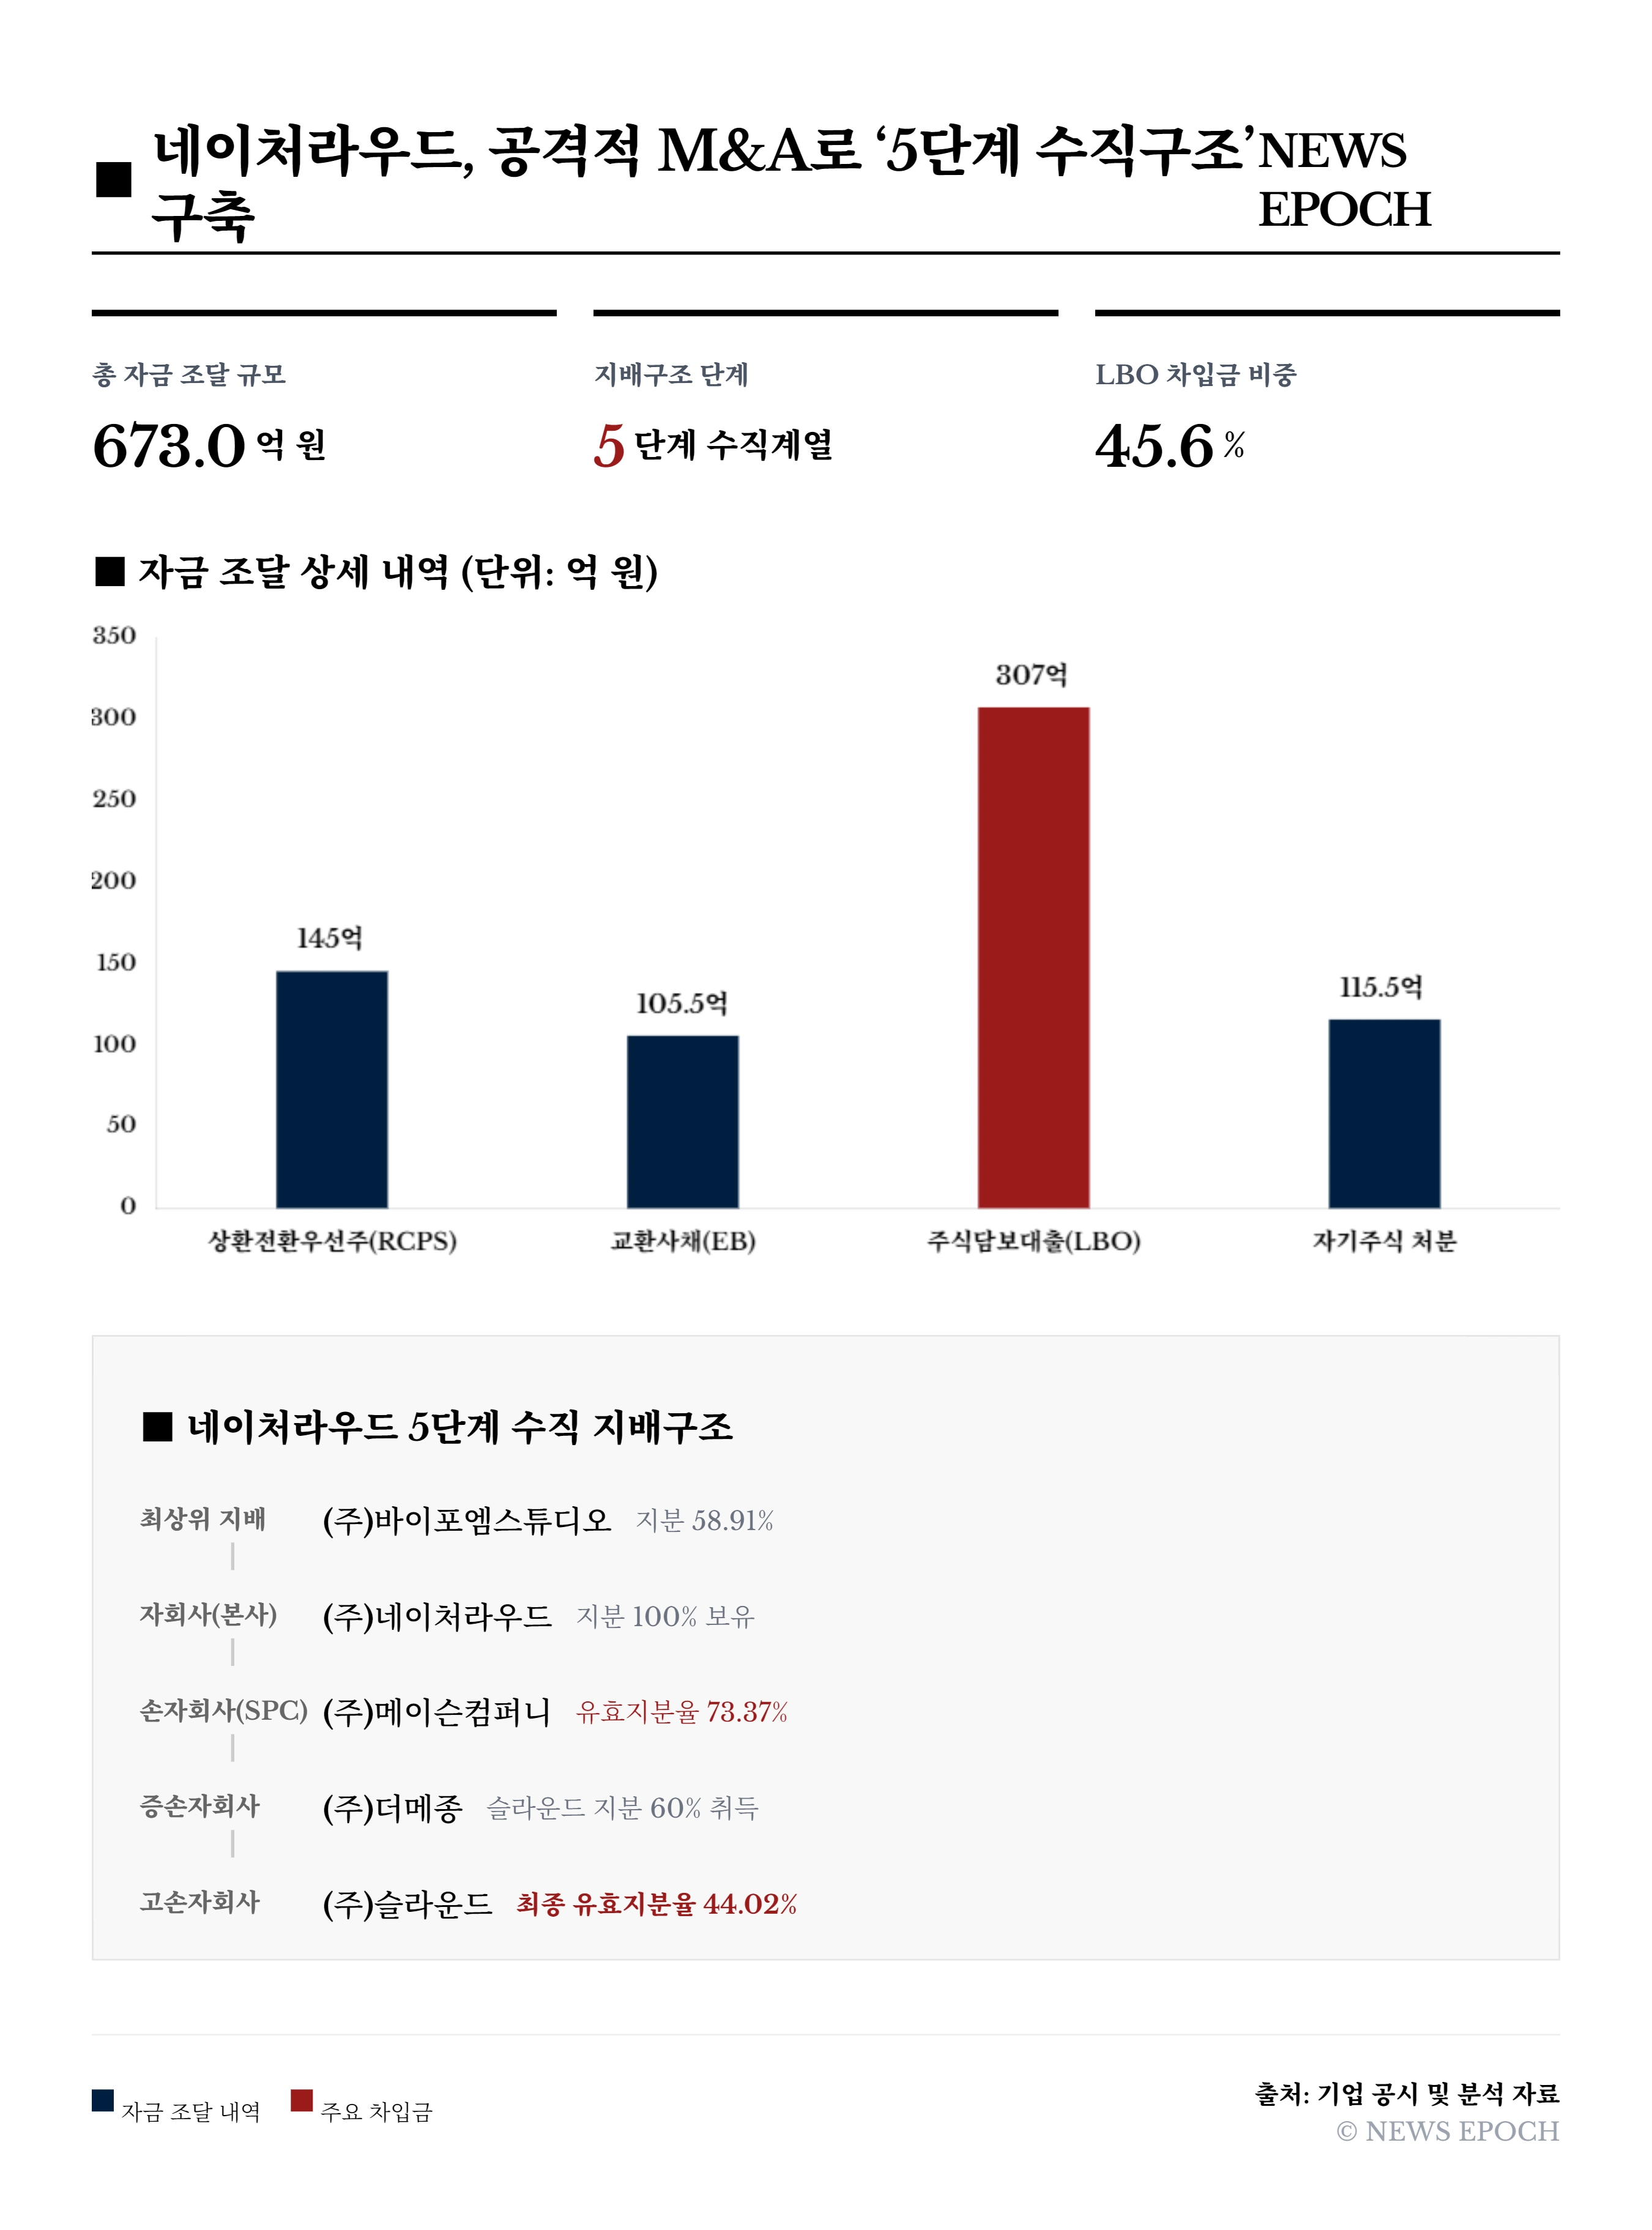
Natureloud's M&A process was so aggressive and sophisticated that it was reminiscent of a private equity (PE) fund. First, instead of the head office stepping up directly, it put forward its subsidiary 'Mason Company Co., Ltd.', which has the characteristics of a special purpose company (SPC), in early 2025. On February 12, 2025, the day of The Maison's acquisition, Mason Company issued redeemable convertible preference shares (RCPS) worth 14.5 billion won to secure initial ammunition. In particular, it was revealed that even key executives of Natureloud participated as members of this investment association.
The most eye-catching part is the use of the typical leveraged buyout (LBO) technique. Mason Company immediately provided the acquired shares of The Maison Co., Ltd. (worth approximately 39.6 billion won) as collateral to secondary financial sectors such as Pepper Savings Bank, bringing in about 30.7 billion won in borrowings. In effect, it covered the M&A payment by borrowing money again using the acquired company's assets as collateral.
The parent company, Natureloud's head office, also devoted all its efforts to raising funds. In August 2025, it additionally issued exchangeable bonds (EB) targeting its treasury shares as exchange objects in three tranches totaling 10.5 billion won, while directly disposing of its own treasury shares to finance an additional 11.5 billion won in cash.
As a result, Natureloud swallowed the companies by gathering external ammunition and debt amounting to 60 billion won, including 14.5 billion won in preferred shares, 10.55 billion won in corporate bonds, 30.7 billion won in stock-collateralized loans, and 11.55 billion won in treasury stock sales. Through this, it completed a deep 5-stage vertical governance structure leading from 'BY4M Studio (top-tier controlling company) ➔ Natureloud ➔ Mason Company (SPC) ➔ The Maison ➔ Slound'.
The Shell Company is Out… The 'Two-Track Listing' Obligation of the Head Office and Grand-Subsidiary
Strongly suggesting the intervention of highly skilled structured finance experts internally, this unconventional strategy can maximize shareholder value with a massive leverage effect if successful. The core condition supporting this giant lever is indeed a 'listing (IPO)'.
The interesting point is that the heavy burden of listing is placed not on 'Mason Company', the shell company put forward for the acquisition, but on both 'Natureloud's head office' positioned above and its grand-subsidiary 'The Maison Co., Ltd.' positioned below, through a two-track approach.
The first track is Natureloud's (head office) direct listing obligation. In accordance with contracts signed with common stock investors worth 12.6 billion won and exchangeable bond (EB) investors worth 10.55 billion won, Natureloud must directly complete its listing by December 31, 2026. Furthermore, a strict hurdle is imposed requiring it to achieve a market capitalization of 200 billion won or more after the public offering.
The second track is the listing and merger obligation of the subsidiary, The Maison Co., Ltd. According to the contract signed with existing shareholders (non-controlling shareholders) of The Maison Co., Ltd., even if Natureloud successfully goes public, the three companies—Natureloud, Mason Company, and The Maison—must complete a merger. If this merger falls through, or if The Maison Co., Ltd. itself fails to list independently within the set deadline, a fearsome counterattack from the investors will begin.
'High Risk High Return'… Put Option Penalties of 10~15% Annual Compound Interest Lurking Everywhere
Put option penalties, which are triggered if the schedule, merger, or corporate value goals deviate even slightly, are strongly in place.
If Natureloud fails to list and achieve a market capitalization of 200 billion won by the end of 2026, common stock and exchangeable bond investors can claim early repayment, demanding the repurchase of their shares with a 10% annual compound interest added to the principal. The 14.5 billion won in preferred shares (RCPS) issued by Mason Company is also subject to a guaranteed yield to maturity of 12% annual compound interest, meaning that in the event of failure to redeem, investors will directly demand the purchase of their shares from Natureloud's head office and its parent company.
A put option is also attached to The Maison Co., Ltd. If the three-way merger falls through or The Maison's independent listing fails, existing shareholders can demand their stakes be bought out at approximately 1.91 million won per share, plus a high interest rate of a whopping 15% annual compound interest.
Above all, it is thoroughly designed so that the arrow of all failures ultimately points to the joint and several liability of the top-tier controlling company, BY4M Studio, without any 'cutting off the tail' (evading responsibility). Capital markets are focusing their attention on Natureloud's cliff-edge showdown to see whether it can prove the magic of leverage by overcoming both the IPO hurdle of a 200 billion won market capitalization and the demanding merger conditions, armed with its aggressive capitalization, or whether it will detonate a massive put option bomb.
Company financial data, investment reports, and startup analysis — all in one place
Explore PitchdeckCurated news, every week — straight to your inbox
Every Friday · Unsubscribe anytime