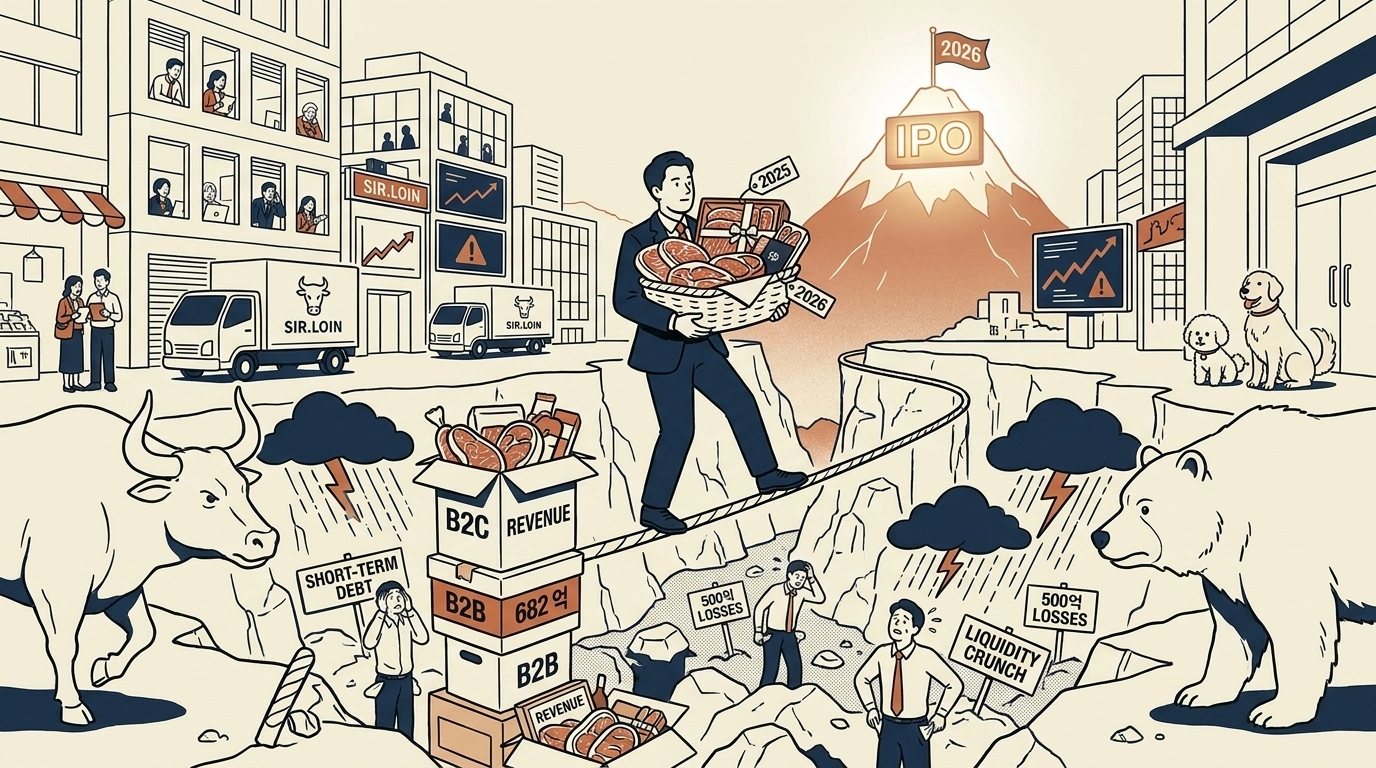
Food tech startup SIR.LOIN is accelerating its initial public offering (IPO) after recording remarkable revenue growth, driven by special holiday demand and strong performance in its B2B (business-to-business) operations. Although aiming to enter the KOSDAQ market by selecting NH Investment & Securities and Hana Securities as its underwriters, the accumulated deficit of around 50 billion won and severe short-term liquidity drought hidden behind its ledger are pointed out as the 'mountains' SIR.LOIN must overcome ahead of its listing.
'The Light': Explosive Top-Line Growth, B2B/B2C Dual Success, and a Green Light for Turning a Profit
Co-founded in 2017 by Seoul National University alumni CEO Byun Joon-won and Vice CEO Kim Ji-soo, along with Chief Product Officer (CPO) Han Deok-woo, a former Hanwoo (Korean beef) auctioneer, SIR.LOIN has been pioneering the premium Hanwoo market armed with AI-based meat selection and proprietary aging technology.
The most powerful weapon in the preliminary IPO screening will undoubtedly be its 'overwhelming growth potential'. SIR.LOIN's revenue has recorded steep vertical increases every year, growing from approximately 26.6 billion won in 2022 to around 33.7 billion won in 2023, 55.6 billion won in 2024, and about 68.2 billion won in 2025. In the B2C (business-to-consumer) sector, the company has established itself as a representative brand for holiday gifts with luxurious packaging and excellent freshness, recently surpassing 80,000 sets in holiday aged Hanwoo set sales.
Its new growth engine, the B2B platform 'Bondaero,' has also successfully settled into the market, exceeding 100 million won in monthly settlements after the launch of vendor product sales. The realization of such economies of scale is leading to profitability improvements. The operating loss, which amounted to 10.1 billion won in 2023, plummeted to about 2.7 billion won in 2024, and the cost ratio improved from 73% to 69%, while the SG&A (Selling, General and Administrative) expense ratio improved from 39% to 31%, lighting up the green signal for reaching the break-even point (BEP). The company is also exploring global expansion, including pushing for the export of Hanwoo energy sticks to Hong Kong.
The Cleared Dark Clouds: Removing the 'Going Concern Uncertainty' Tag and Giving a Green Light for IPO
The biggest good news for SIR.LOIN ahead of its IPO is that it has finally removed the tag that was the largest source of anxiety in its financial statements. External auditors had pointed out every year in the 2023 and 2024 audit reports that there was "a material uncertainty that may cast significant doubt on the entity's ability to continue as a going concern," citing the scale of net losses and current liabilities. This phrasing was considered a critical disqualifying factor during the preliminary listing screening and was thus seen as a mountain that had to be overcome.
However, SIR.LOIN fully resolved these concerns in its 2025 audit report and received an unqualified opinion. This was thanks to proving a clear performance turnaround by drastically reducing SG&A expenses such as advertising costs while increasing revenue by over 30% year-on-year, improving its cost ratio from 73% to 69%, and generating a surplus of 1.2 billion won in the first quarter. Having cleared the biggest obstacle to its listing, SIR.LOIN can now prepare for the preliminary IPO screening with much lighter steps.
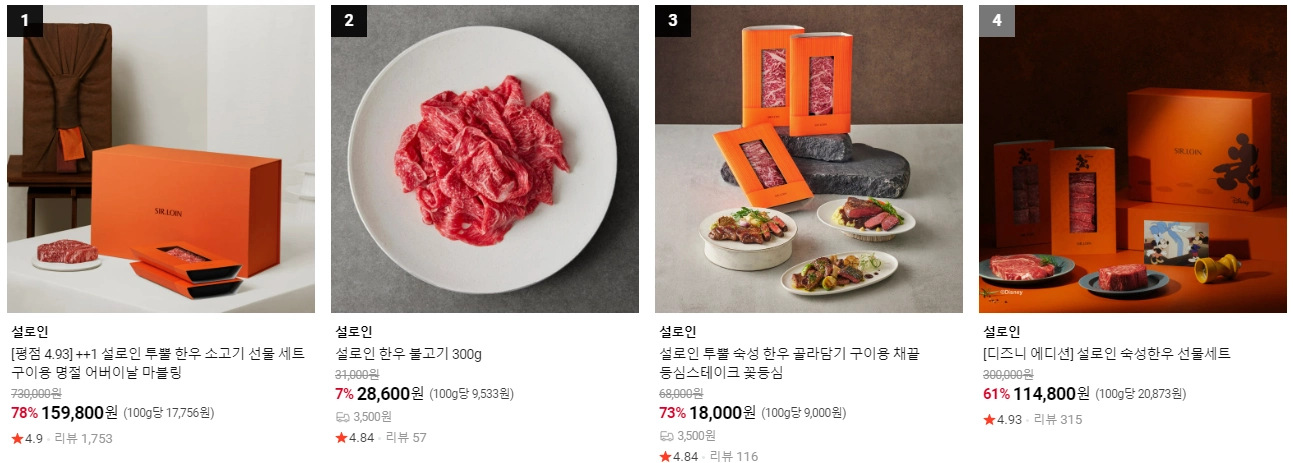
[Source: SIR.LOIN Naver Store]
The Dilemma of Accounting Standards and Liquidity Drought... Financial Pressure Reaching the Chin
The accounting confusion experienced while preparing for the IPO also left scars on the financial statements. SIR.LOIN adopted K-IFRS (Korean International Financial Reporting Standards) in 2023 in preparation for its listing, but this caused the existing Redeemable Convertible Preference Shares (RCPS) to be classified as liabilities, plunging the total equity into minus (-) 47.4 billion won (on a consolidated basis) and falling into complete capital impairment. Eventually, it reverted to the General Accounting Standards for Unlisted Entities (K-GAAP) in 2024, turning preferred shares back into equity and thereby avoiding numerical capital impairment, but this was not an improvement in fundamentals.
Accordingly, SIR.LOIN defended its capital in 2024 by reflecting a revaluation gain of about 9.3 billion won through the revaluation of its land holdings, recording a cumulative revaluation surplus of 12.5 billion won. However, the company's core assets, land and buildings (book value of approximately 59 billion won), are already tied up as collateral for 37.2 billion won to the Korea Development Bank and others, limiting its capacity for further asset securitization.
The pressure for short-term funding is also at a high level. As of the end of 2025, SIR.LOIN's current assets that can be cashed within one year amount to only 7.6 billion won, while the current liabilities to be repaid within one year reach 20.7 billion won. The company is facing short-term borrowing pressures of 15.4 billion won, which is the sum of 10.5 billion won in short-term borrowings and 4.9 billion won in the current portion of long-term borrowings, yet its cash and cash equivalents are just over 1.8 billion won. The quality of its debt is also a concern, as it includes 5.5 billion won in individual shareholder loans with an annual interest rate of 12% in addition to real estate mortgage loans, keeping annual interest expenses at a relatively high level.
The Key to a Successful Listing: Pre-IPO Success and Proof of Financial Soundness
Ultimately, the key prerequisites for SIR.LOIN to cross the threshold of listing are a 'perfect turnaround to surplus' and 'capital expansion through a pre-IPO'.
To pass the stricter exchange screening criteria, clean financial indicators that lower the debt ratio and prove short-term debt repayment capabilities are essential. It is a very encouraging sign that entering the first half of 2025, the company attracted a sole new investment of 5 billion won from Magna Investment and improved its debt ratio by converting 5 billion won of existing convertible bonds into shares. Follow-on (subsequent) investments from existing investors, such as the 2 billion won infusion from Enlight Ventures and SNU Holdings in the past, are also adding weight to the company's potential to achieve BEP.
The case where industry competitor Meatbox Global withdrew its listing due to sluggish demand forecasting at the final stage of the listing review, despite its surplus trend, has significant implications. Market attention is focused on whether SIR.LOIN can fully prove its fundamental strength (liquidity and profit-generating capability) commensurate with its overwhelming growth potential, clear the shadows of its financial structure, and achieve the splendid feat of becoming the first listed company in the Hanwoo industry.
Company financial data, investment reports, and startup analysis — all in one place
Explore PitchdeckCurated news, every week — straight to your inbox
Every Friday · Unsubscribe anytime