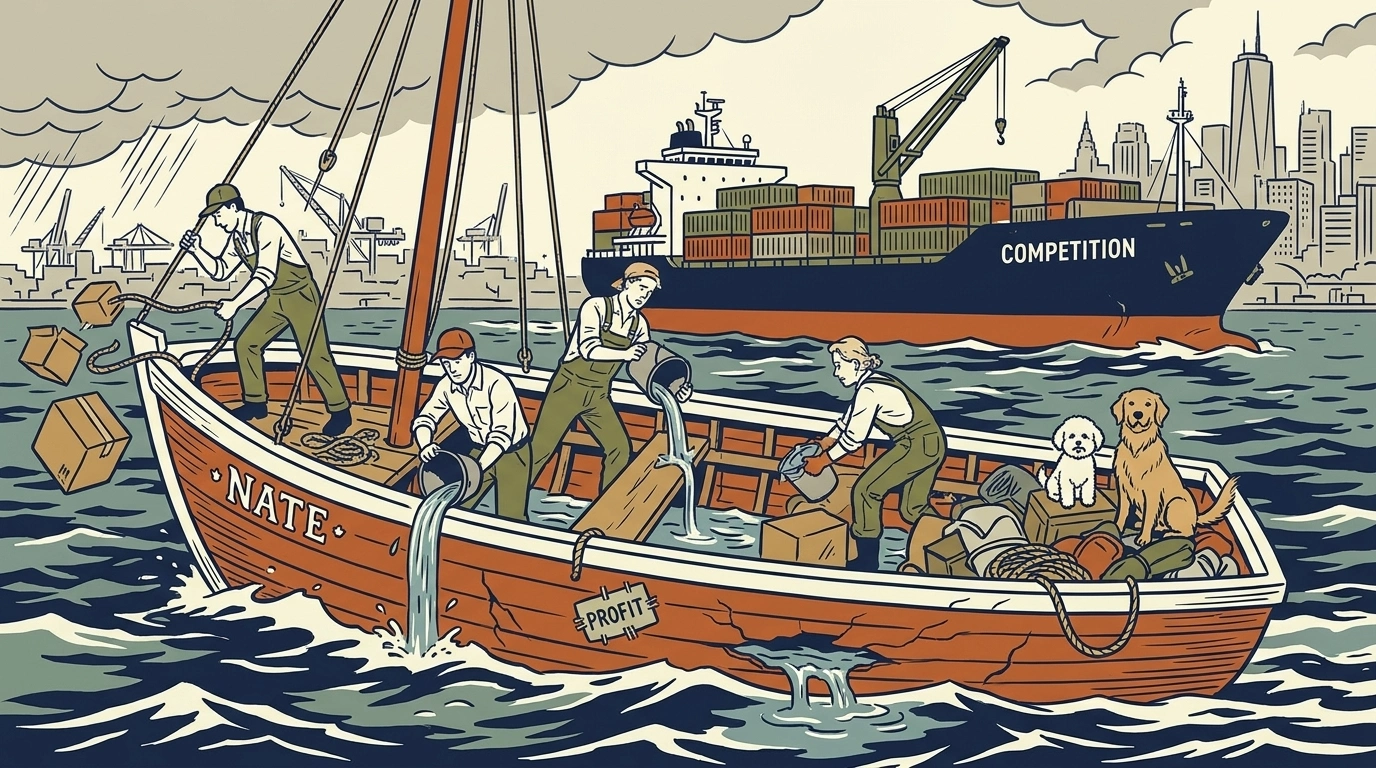
Once considered one of the top three domestic portals along with NAVER and Daum (Kakao) after acquiring Empas, Nate Communications (formerly SK Communications) continues its difficult survival game after being sold to Samgoo FS. Although the company recently announced that it achieved a monthly profit for the first time in 174 months, the reality shown by its financial statements is not very optimistic. Regarding the Quality of Earnings of this profit, opinions are currently leaning heavily toward it being the result of 'cost control' rather than 'structural improvement'.
Endlessly Declining Revenue and Severe Capital Impairment
Looking at the revenue and profit/loss trends over the five years from 2021 to 2025, the weakening of its competitiveness as a platform is evident. Operating revenue (sales), which was about 30.2 billion KRW in 2021, stood still at about 30.5 billion KRW in 2022, and then drew a steep downward curve every year to 28.4 billion KRW in 2023, 24.6 billion KRW in 2024, and 21.2 billion KRW in 2025. The operating loss also failed to escape the swamp of chronic annual deficits, posting losses of 6.9 billion to 11.7 billion KRW each year after recording a deficit of 9.7 billion KRW in 2021.
An aspect to note is financial stability. As of the end of 2025, the company's paid-in capital is only 21.7 billion KRW, but the accumulated undisposed deficit amounts to a staggering 215.36 billion KRW (-215,360,974,287 KRW), severely eroding its capital. Total equity also shrank by more than half from about 24.7 billion KRW in 2021 to about 9.8 billion KRW as of 2025. Its capital capacity is continuously weakening, posing a significant threat to financial stability without additional capital expansion or fundamental profitability improvement.
Operating Cash Flow 'Perpetually Negative'... Holding Out by Selling Non-Operating Assets
It is also a major problem that cash is being depleted the more they operate. Looking at the cash flow generated from operations, it was -9.17 billion KRW in 2021, -6.02 billion KRW in 2022, -6.35 billion KRW in 2023, -9.00 billion KRW in 2024, and -7.57 billion KRW in 2025, failing to generate a positive (+) cash flow even once in the last five years.
To defend against this, the company has supplemented its liquidity by selling investment shares in related companies. The company, which was a major shareholder of Konan Technology Inc., disposed of all of these stakes in the market over 2022 and 2023. In particular, looking at the 2023 cash flow statement, it can be seen that a massive amount of cash, approximately 22.3 billion KRW, flowed in from the disposal of investments in related companies. It has been surviving on a typical 'Asset Liquidation' strategy, filling the cash lost in its main business through the sale of non-operating assets (stakes). However, in a situation where fundamental operating cash flow is not improving, even these core liquidable assets are analyzed to be virtually almost exhausted at present.
Change of Major Shareholder and 'Contraction-Oriented Holding Out'
The company, which was a 100% subsidiary of SK Telecom, saw its largest shareholder change to Samgoo FS Co., Ltd. (100% stake) through a stock transfer transaction in January 2025. Following the change of the major shareholder, the company appears to be demonstrating a so-called 'contraction-oriented holding out' by thoroughly blocking cash outflows for acquiring new intangible assets (minimizing CAPEX) and defending fixed costs using only the minimal incoming maintenance revenue. Although it has put forward a strategy to focus on retention-type services such as Nate Pann and NateOn instead of search, extreme investment reduction lies behind it.
The recently announced news of a monthly profit for the first time in 174 months also requires careful examination of its substance. The core issue is whether this profit comes from a 'rebound in revenue (Top-line)' or from extreme 'cost-cutting'.
Realistically, it is very difficult for an IT platform to recover the market share lost to giant competitors like NAVER and Kakao. Therefore, this profit is highly likely not a result of an influx of new traffic or an increase in advertising unit prices, but rather the result of company-wide 'cost control', such as the liquidation of marginal business units, reduction of marketing expenses, minimization of server maintenance costs, and large-scale workforce reduction carried out immediately after the change of the major shareholder. According to Nate Communications' employment data, the number of employees, which was close to 200 in 2024, is understood to have plummeted to the 80s as of March 2026.
The Clear Limits and Remaining Risks of a 'Recession-Type Profit'
There is a clear limit to a recession-type profit created by strictly controlling costs. Even if a profit is generated, if the revenue itself is declining compared to the same period last year, this means its value as a platform is low. The complete halt of investments for platform advancement can become a poison that accelerates the deterioration of service quality and the departure of remaining users in the long term.
We are now in an era where the entire search and portal market is under a strong threat due to the universalization of generative AI. It is time to watch how, beyond achieving a short-term profit under the leadership of the new major shareholder, they will navigate the financial crisis and market crisis pushing them to the edge of the cliff.
Company financial data, investment reports, and startup analysis — all in one place
Explore PitchdeckCurated news, every week — straight to your inbox
Every Friday · Unsubscribe anytime