'HealthHub' that Dreamed of Innovation in Medical Data Exchange
HealthHub is an IT company specializing in cloud-based healthcare solutions, having led digital innovation in medical imaging and information systems such as Picture Archiving and Communication Systems (PACS), Electronic Medical Records (EMR), and AI diagnostic support. Based on its global medical imaging SaaS platform, it supported fast and secure data exchange among hospitals, medical staff, and patients, receiving high expectations from the industry.
Highly evaluated for such technological prowess and vision, the company succeeded in attracting a large-scale investment of approximately 20 billion won from leading institutional investors such as DS Asset Management, Timefolio Asset Management, AJU IB Investment, and Shinhan Venture Investment in 2021. At the time, HealthHub was considered such a promising venture company that its corporate value estimated by the market reached about 87 billion won.
Continuous Revenue Decline and Persistent Deficits
However, looking at HealthHub's recent financials, the company's situation appears difficult. The company is simultaneously experiencing a reduction in size and deteriorating profitability. Consolidated revenue, which maintained the 5 billion to 6 billion won range up until 2021 and 2022, decreased every year, halving to about 2.6 billion won in 2025. Furthermore, as massive operating losses and net losses have accumulated over five consecutive years, it has not once been able to escape from a state of persistent deficit.
[Source: HealthHub Website]
Uncertainty as a Going Concern and Complete Capital Impairment
One of the problems the company currently faces is 'material uncertainty related to going concern'. In 2025 alone, it recorded a continuing operating loss of 5.7 billion won and a net loss of 5 billion won. As such unbearable deficits continued, the accumulated deficit snowballed, and ultimately, the company fell into a state of 'complete capital impairment' with total equity standing at minus (-) 3.34015 billion won as of the end of the current period.
Funding sources are also continuing to dry up. If this situation continues, the possibility of a liquidity crisis will increase. Current liabilities that must be paid off immediately exceed current assets that can be converted into cash by 4.2 billion won. The scale itself may not be large, but considering the company's revenue and the scale of the deficit, it is hard to easily ignore. Without external emergency funding or groundbreaking improvements to the financial structure, the company could face an unmanageable situation. Such financial difficulties are also clearly revealed by the reduction in organizational size. The number of employees, which stood at around 69 in 2023, is understood to have plummeted to 28 as of 2026, going through restructuring and personnel departures.
Collapse of Sales Structure and Risk of Customer Concentration
A fundamental ticking time bomb is the fact that the costs of maintaining the company are at an unbearable level compared to its revenue-generating capacity. Compared to the revenue the company generates in a year (about 2.6 billion won), the costs of maintaining the company, including SG&A expenses (about 6.7 billion won), are overwhelmingly large. Due to this anomalous operating structure where it spends more than 2.5 times what it earns, the company's operational runway is helplessly shrinking.
Even the revenue that does occur is exceedingly fragile, as it extremely relies on specific clients. Of the total revenue for the current period of about 2.6 billion won, 1.5 billion won—over 60% of total revenue—was generated from just one specific client. Adding the combined revenue of the top three clients comes to 2.2 billion won, accounting for 84.5% of total revenue. If a contract with a key client is terminated or if the company faces pressure to lower unit prices, it appears to have no ability to defend against or absorb the shock.
Even the overseas business, which was considered a future growth engine, eventually underwent withdrawal procedures, resulting in a painful failure. Through its board of directors during the current period, the company decided to sell its U.S. regional subsidiary 'HEALTHHUB INC.' and classified it as a discontinued operation. This effectively formalizes the failure of its expansion into the global market, which not only signifies massive sunk costs invested thus far, but also may show that the company's major future growth engine has been lost.
Urgent Need to Secure a Breakthrough to Overcome the Crisis
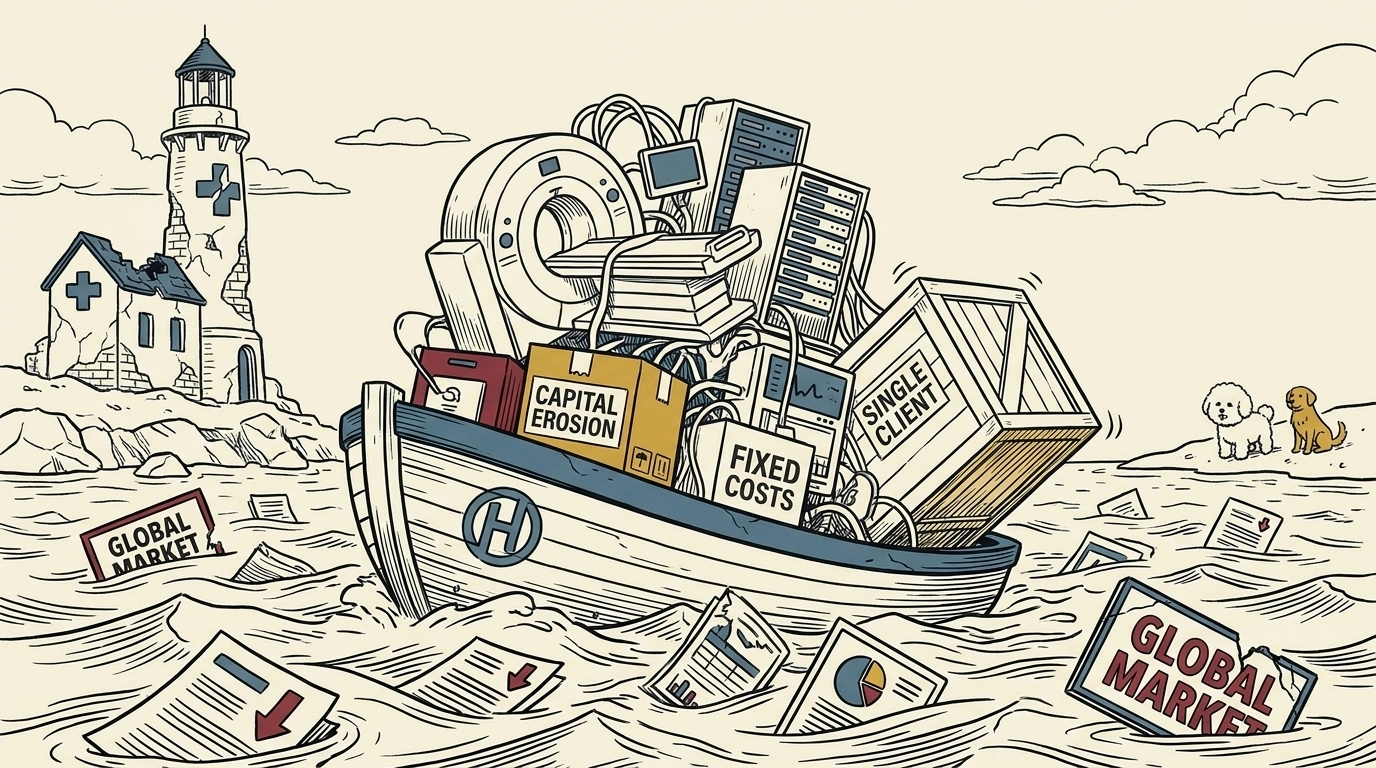
As a result, HealthHub is standing on the edge of a cliff of capital impairment and liquidity depletion, compounded by an overwhelming burden of fixed costs, extreme customer concentration, and the failure of its overseas business.
However, HealthHub is a company whose technological prowess and social value have been recognized in the market, such as by providing cloud transition solutions for small- and medium-sized hospitals and hospitals in vulnerable areas. As it has the underlying strength that once garnered immense attention and expectations from the market and investment firms with an acknowledged corporate value of 87 billion won, there are hopes that it can safely break through the current severe crisis and soar once again through painful business restructuring and additional investment attraction.
Company financial data, investment reports, and startup analysis — all in one place
Explore PitchdeckCurated news, every week — straight to your inbox
Every Friday · Unsubscribe anytime