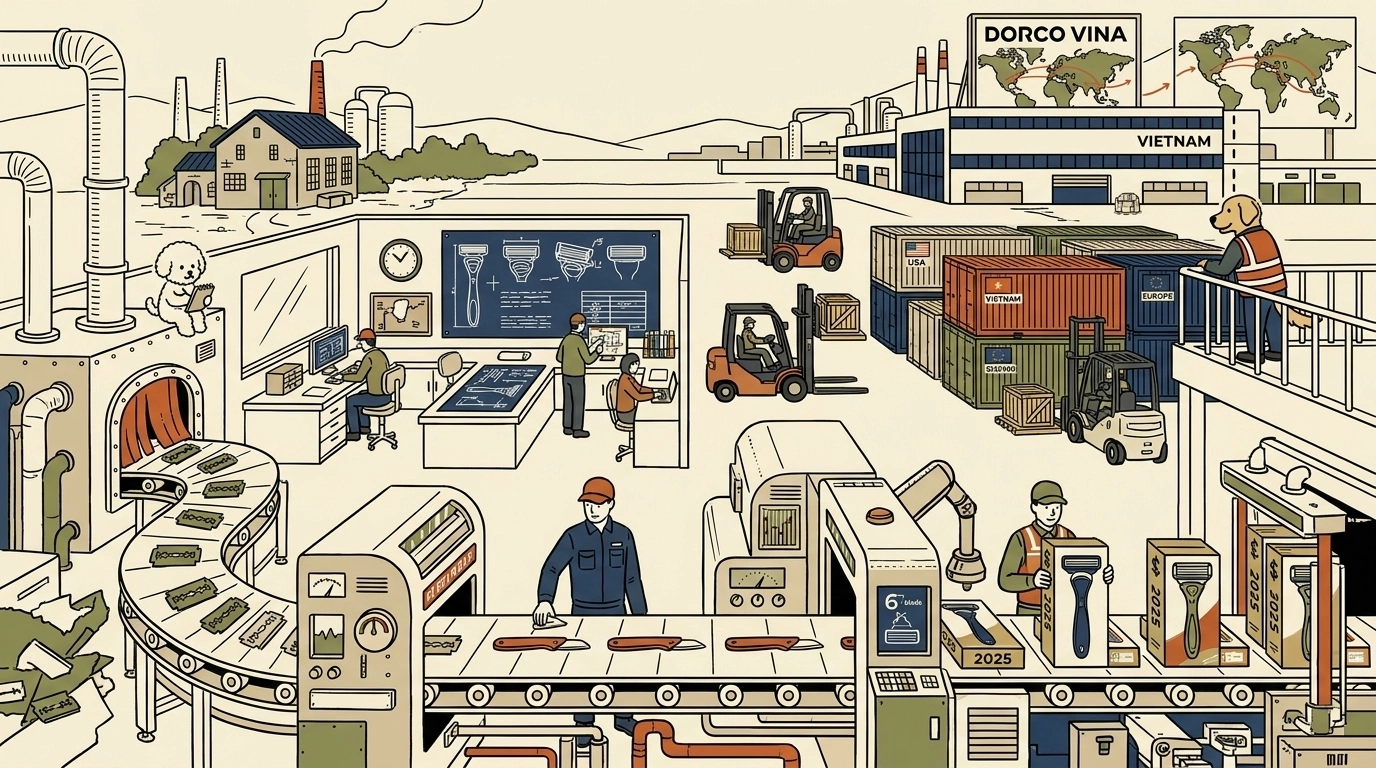
'Dongyang Light Metal Industries,' a small factory that started in 1955 by picking up discarded razor blades from the US military to make stationery knives, has grown 70 years later into 'Dorco,' a global hidden champion exporting products to over 130 countries worldwide. In the late 1980s, it suffered a painful crisis where sales plummeted by nearly 80% due to the offensive of foreign brands, but it devoted itself to research and development (R&D), successively creating the world's first 6-blade and 7-blade razors and establishing itself as a powerhouse with the fourth-largest market share.
According to a report by global market research firm Mordor Intelligence, the global razor market is projected to grow from 12.06 billion USD (approximately 18.5 trillion KRW) in 2026 to 14.05 billion USD (approximately 21.6 trillion KRW) in 2031, with a compound annual growth rate (CAGR) of 3.90%. In particular, the Asia-Pacific region is leading the fastest growth, creating a very favorable tailwind for Dorco's global territorial expansion.
Top-Line Growth Rivaling Conglomerates and 'Next-Level' Profit Quality
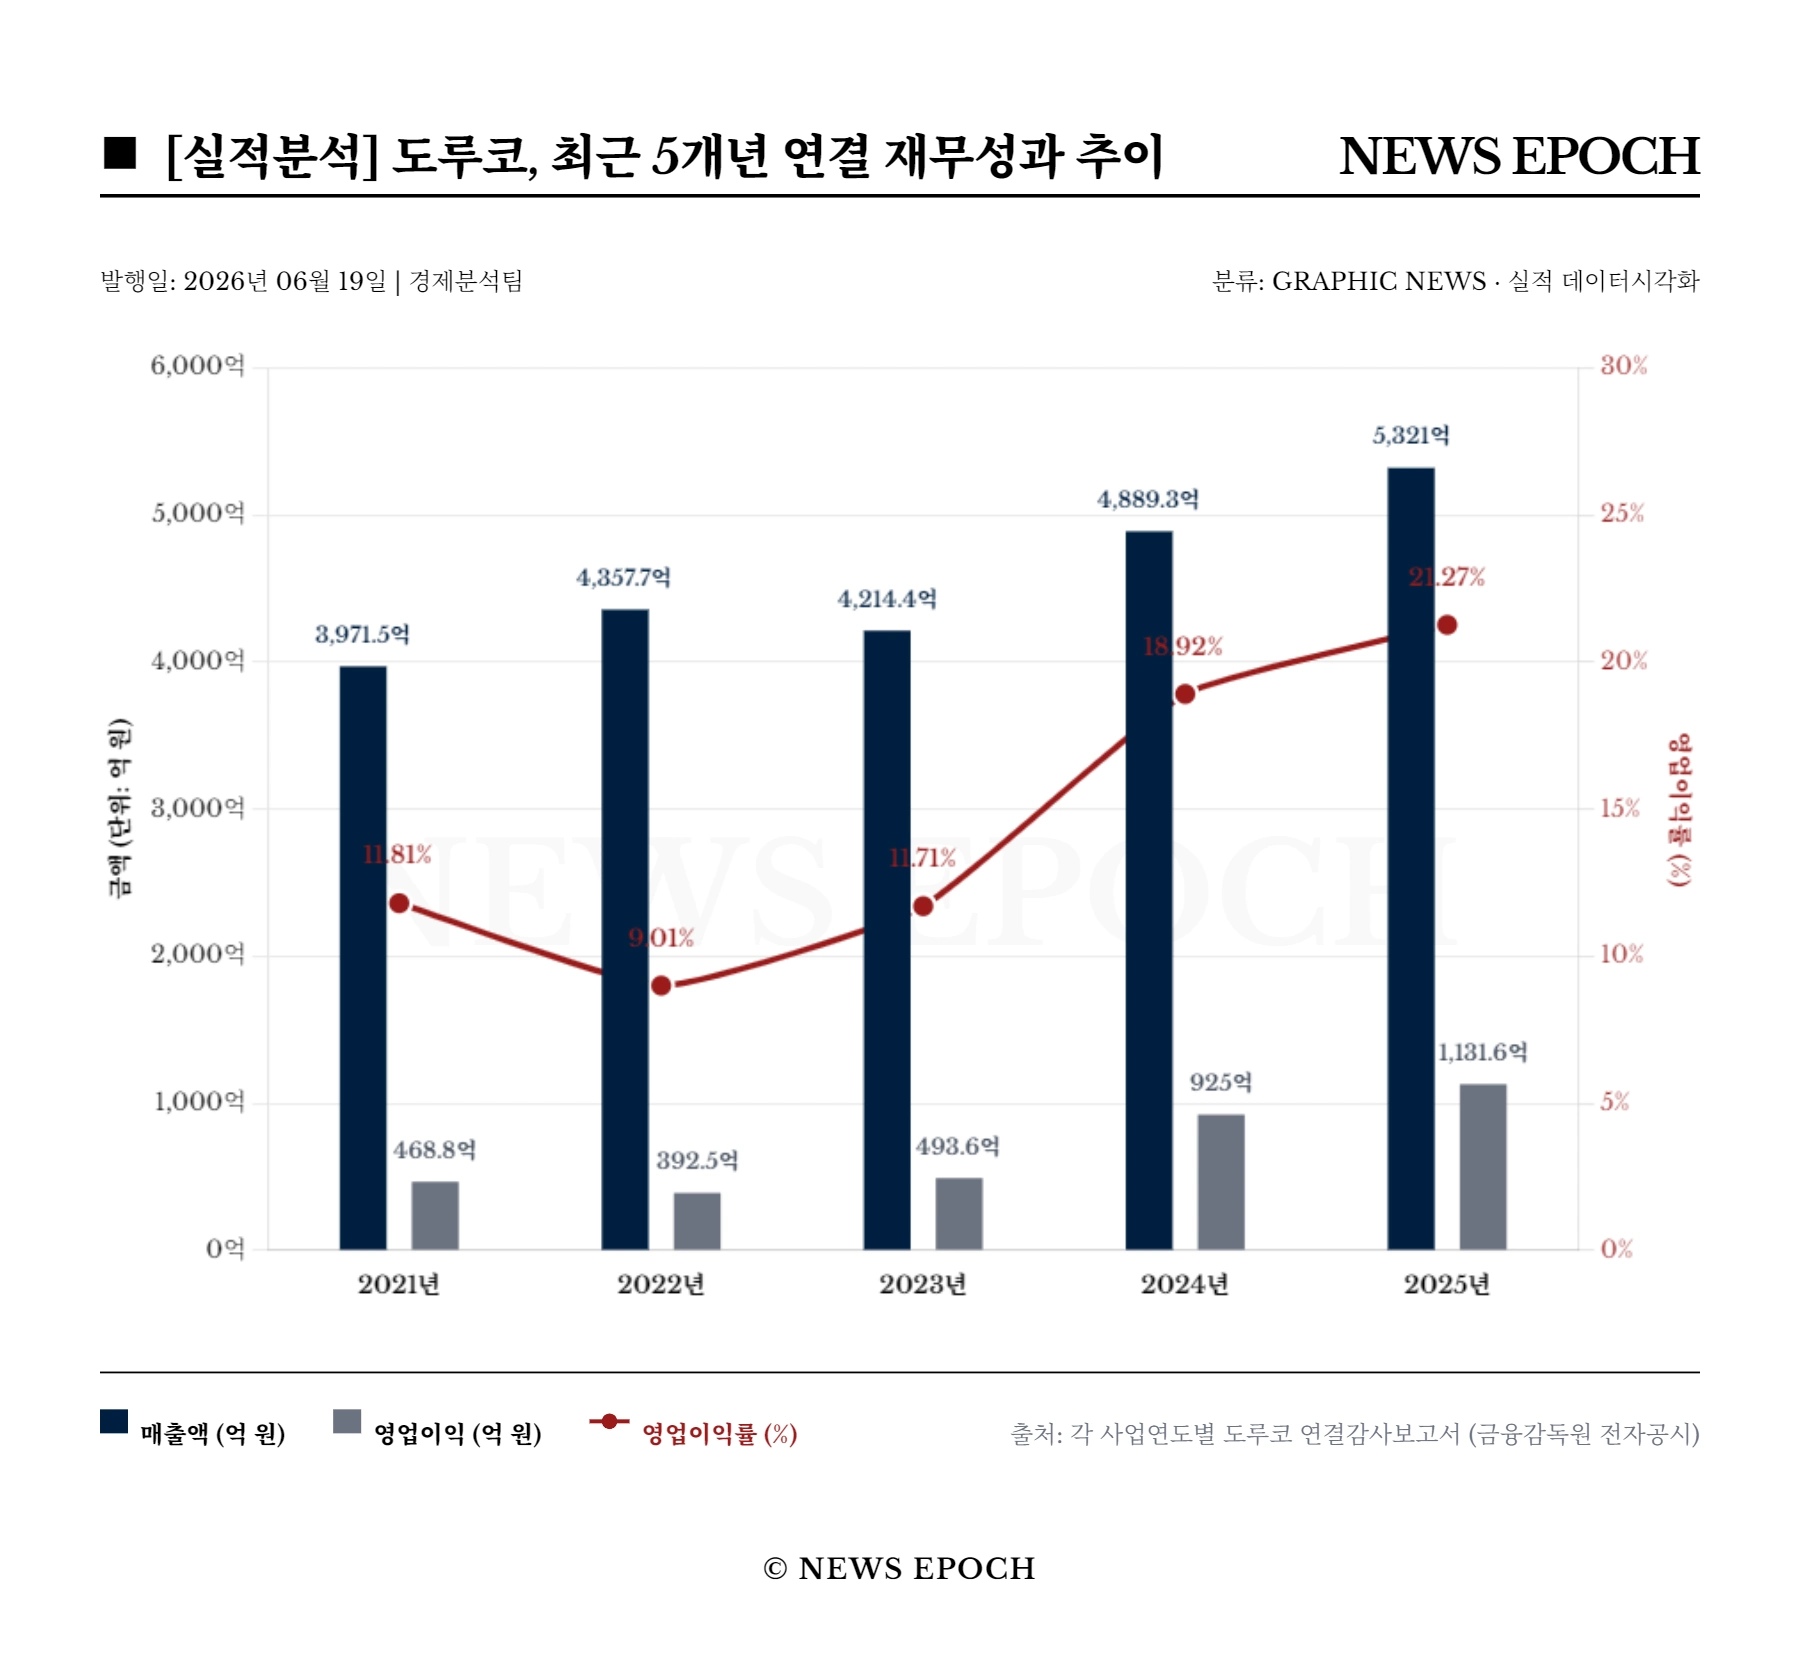
If the Dorco of the past was simply a 'cost-effective national brand,' the Dorco of the past five years has evolved into a 'global cash cow' equipped with formidable profitability. The most prominent feature is undoubtedly the simultaneous growth of both top-line revenue and profit. Dorco's consolidated sales started at 397.1 billion won in 2021, trended steadily upward every year without a single dip, and finally easily surpassed the 500 billion won mark by recording 532.1 billion won in 2025.
Even more encouraging is the qualitative growth of its profit. Operating profit signaled a leap by recording 92.5 billion won in 2024, and it surpassed 113.1 billion won in 2025, showing a steep surge for two consecutive years. This demonstrates a phenomenal profitability of an 'operating profit margin in the 20% range (approximately 21.3%),' which is extremely difficult for a manufacturing-based company to achieve. Net income, which serves as the ultimate report card, also skyrocketed from 42.7 billion won in 2021 to 116.4 billion won in 2025.
Currently, Dorco's consolidated sales volume is similar to major domestic conglomerates such as HD Hyundai, Hansol Technics, LS Metal, and Celltrion Pharm, and has grown to a level where it stands shoulder to shoulder with foreign-affiliated companies like IBM Korea, HP Korea, and Dyson Korea.
Discarded Low-Margin 'Merchandise' to Grow In-House 'Products'... Cost-to-Sales Ratio Enters the 40% Range
At the core of this explosive improvement in profit margin lies the Dorco management's structural decision for 'portfolio optimization.' Dorco drastically reduced its sales of 'merchandise,' which had low distribution margins and did not significantly contribute to profitability. In fact, merchandise sales, which reached 61.3 billion won in 2024, plummeted by more than half to 25.4 billion won in 2025.
On the other hand, the sales of in-house manufactured 'products,' which carry an absolutely higher margin, significantly increased by 18.8% from 426.3 billion won to 506.4 billion won, completely transforming the company's constitution into a high-profit structure. The results of this portfolio reorganization were immediate. The cost-to-sales ratio, which stood at 59.4% in 2023, dropped to 53.6% in 2024 and further declined to 49.3% in 2025. Lowering the cost ratio to the 40% range means that the direct and indirect costs incurred in manufacturing goods were cut by more than half, thereby explosively expanding the pure profit space.
'Economies of Scale' at the Vietnam Factory and Outstanding Cost Control
Another secret that enabled this cost ratio innovation is 'economies of scale' and exceptional cost control capability. The sales of the Vietnam subsidiary (DORCO VINA), Dorco's core global production base, stood at around 156.8 billion won in 2021, but expanded significantly to 218.4 billion won in 2025, driven by stable factory operations and increased production volume. As the factory utilization rate surpassed a certain threshold, economies of scale went into full swing, leading to a sharp drop in fixed costs such as depreciation allocated per product unit.
Furthermore, it smartly utilized the opportunity of normalized logistics costs. As maritime freight rates—which had skyrocketed due to past global supply chain paralysis—stabilized, Dorco appears to have boldly invested the saved costs into aggressive marketing, including increasing advertising and promotional expenses (from 23.6 billion won to 33.0 billion won) to strengthen global brand awareness. What is surprising is that despite significantly increasing marketing expenses and payment commissions, it perfectly defended its overall cost of sales at a level similar to the previous year (approximately 262.4 billion won), ultimately generating over 20 billion won more in operating profit as a result.
Formidable Cash Generation That Even Sparked 'Aekyung Industrial Acquisition Rumors'
Dorco's financial stability has been maximized as one-off non-operating factors were added to the explosively increased profit from its core business. As the book value of 'land,' a tangible asset on the balance sheet, decreased by about 20.1 billion won, massive proceeds from real estate sales flowed in, which was reflected as a 38.4 billion won gain on disposal of tangible assets under non-operating income. As a result, cash and cash equivalents, which were 128.7 billion won at the end of 2024, surged by a whopping 50% to 192.9 billion won at the end of 2025.
The recent rumors circulating in parts of the market that Dorco was weighing participation in the acquisition bid for Aekyung Industrial, a household goods company valued at around 600 billion won, are also due to such ample cash ammunition. Although it did not step up as a leading candidate or make it official, simply having its name mentioned as a potential buyer in a large-scale M&A market approaching the trillion-won scale is symbolic in itself. This clearly demonstrates how powerfully Dorco's massive cash liquidity (342.4 billion won in current assets at the end of 2024) and capital strength are recognized in the capital market.
Settling into the European Market is the Final Puzzle to Solve Ahead
Even for Dorco, which is drawing a steep upward curve, there remains homework to do. The Vietnam subsidiary, which handles a major pillar of the overall parent company's sales, and the US, the world's largest market (DORCO AMERICA net income of 1.78 billion won, etc.), are maintaining a stable surplus trend and playing the role of a solid foundation.
On the other hand, in the demanding European market, initial cost expenditures for securing local distribution networks and settling in are still ongoing, with the German subsidiary (DORCO EUROPE GmbH) and the newly established French subsidiary (DORCO FRANCE) recording net losses of 2.84 billion won and 400 million won, respectively, for the current period. However, this is strongly characterized as an investment for global territorial expansion, and the scale of the deficit compared to overall sales is minuscule, not at a level to threaten growth. If Dorco, based on its current formidable cash-generating power, manages to put its profitability in the European market on track as well, it is expected to face a greater leap that will shake the landscape of the global razor market in the near future.
Company financial data, investment reports, and startup analysis — all in one place
Explore PitchdeckCurated news, every week — straight to your inbox
Every Friday · Unsubscribe anytime