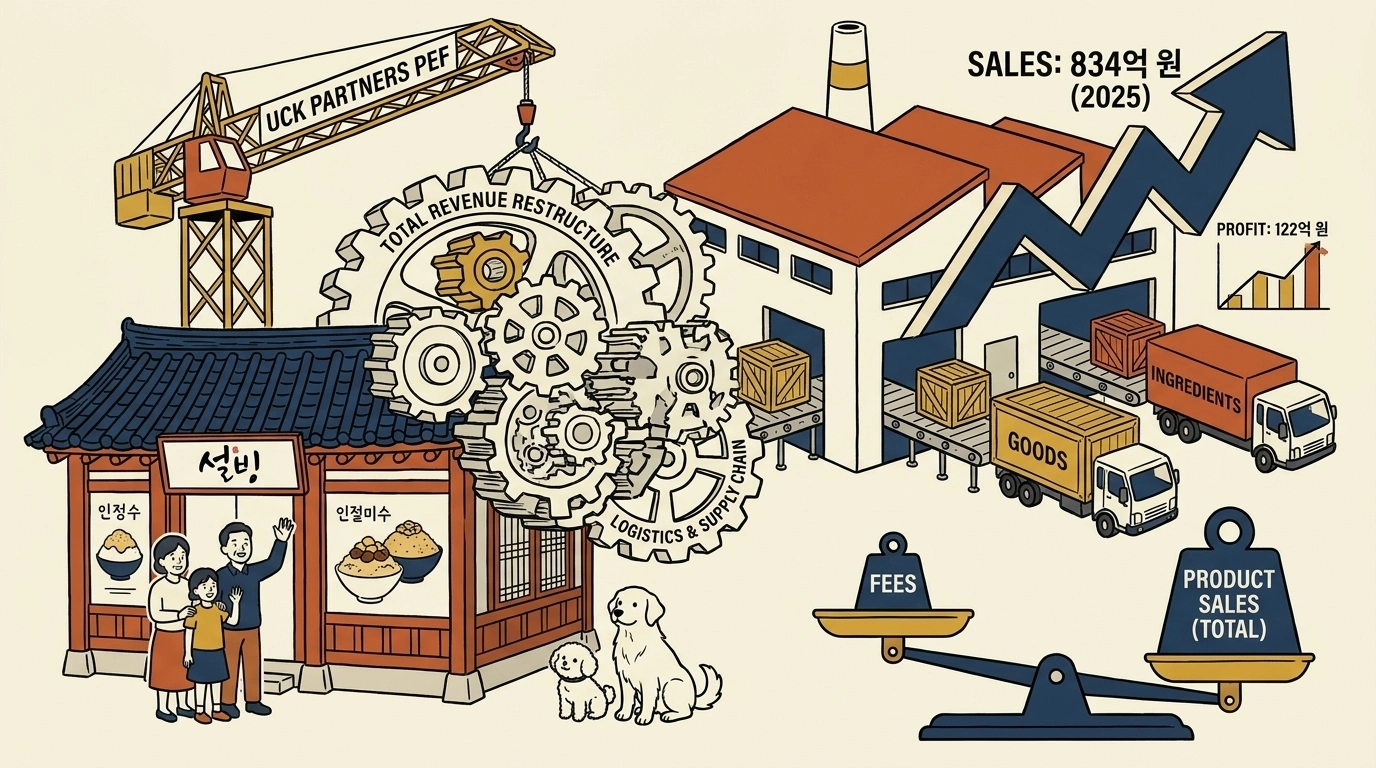
Sulbing's Growth and Transition from Family-Centric Management to a Private Equity Fund (PEF) System
Sulbing is the largest shaved ice dessert (bingsu) franchise in Korea, which started in Nampodong, Busan in 2013 and achieved huge success with desserts utilizing traditional Korean ingredients such as Injeolmi Bingsu. Recently, it is also accelerating its entry into global markets including the United States, Australia, and Southeast Asia.
Prior to 2023, Sulbing was a typical owner-family-centered unlisted company in which related parties, including founder and CEO Jung Seon-hee (40.0%), Jung Chul-min (38.6%), Jung Yong-man (10.7%), and Bae Yang-rye (10.7%), held a 100% stake. However, in 2023, the governance structure was completely reorganized when 'UCK Sulbing LLC', led by private equity fund (PEF) operator UCK Partners, acquired a 100% stake. Along with this, the CEO was replaced from Jung Yong-man to Kim Eui-yeol to further strengthen management expertise.
The Hidden Side of 2025 Performance: Changes in Accounting Revenue Recognition Methods and Internalization of Logistics
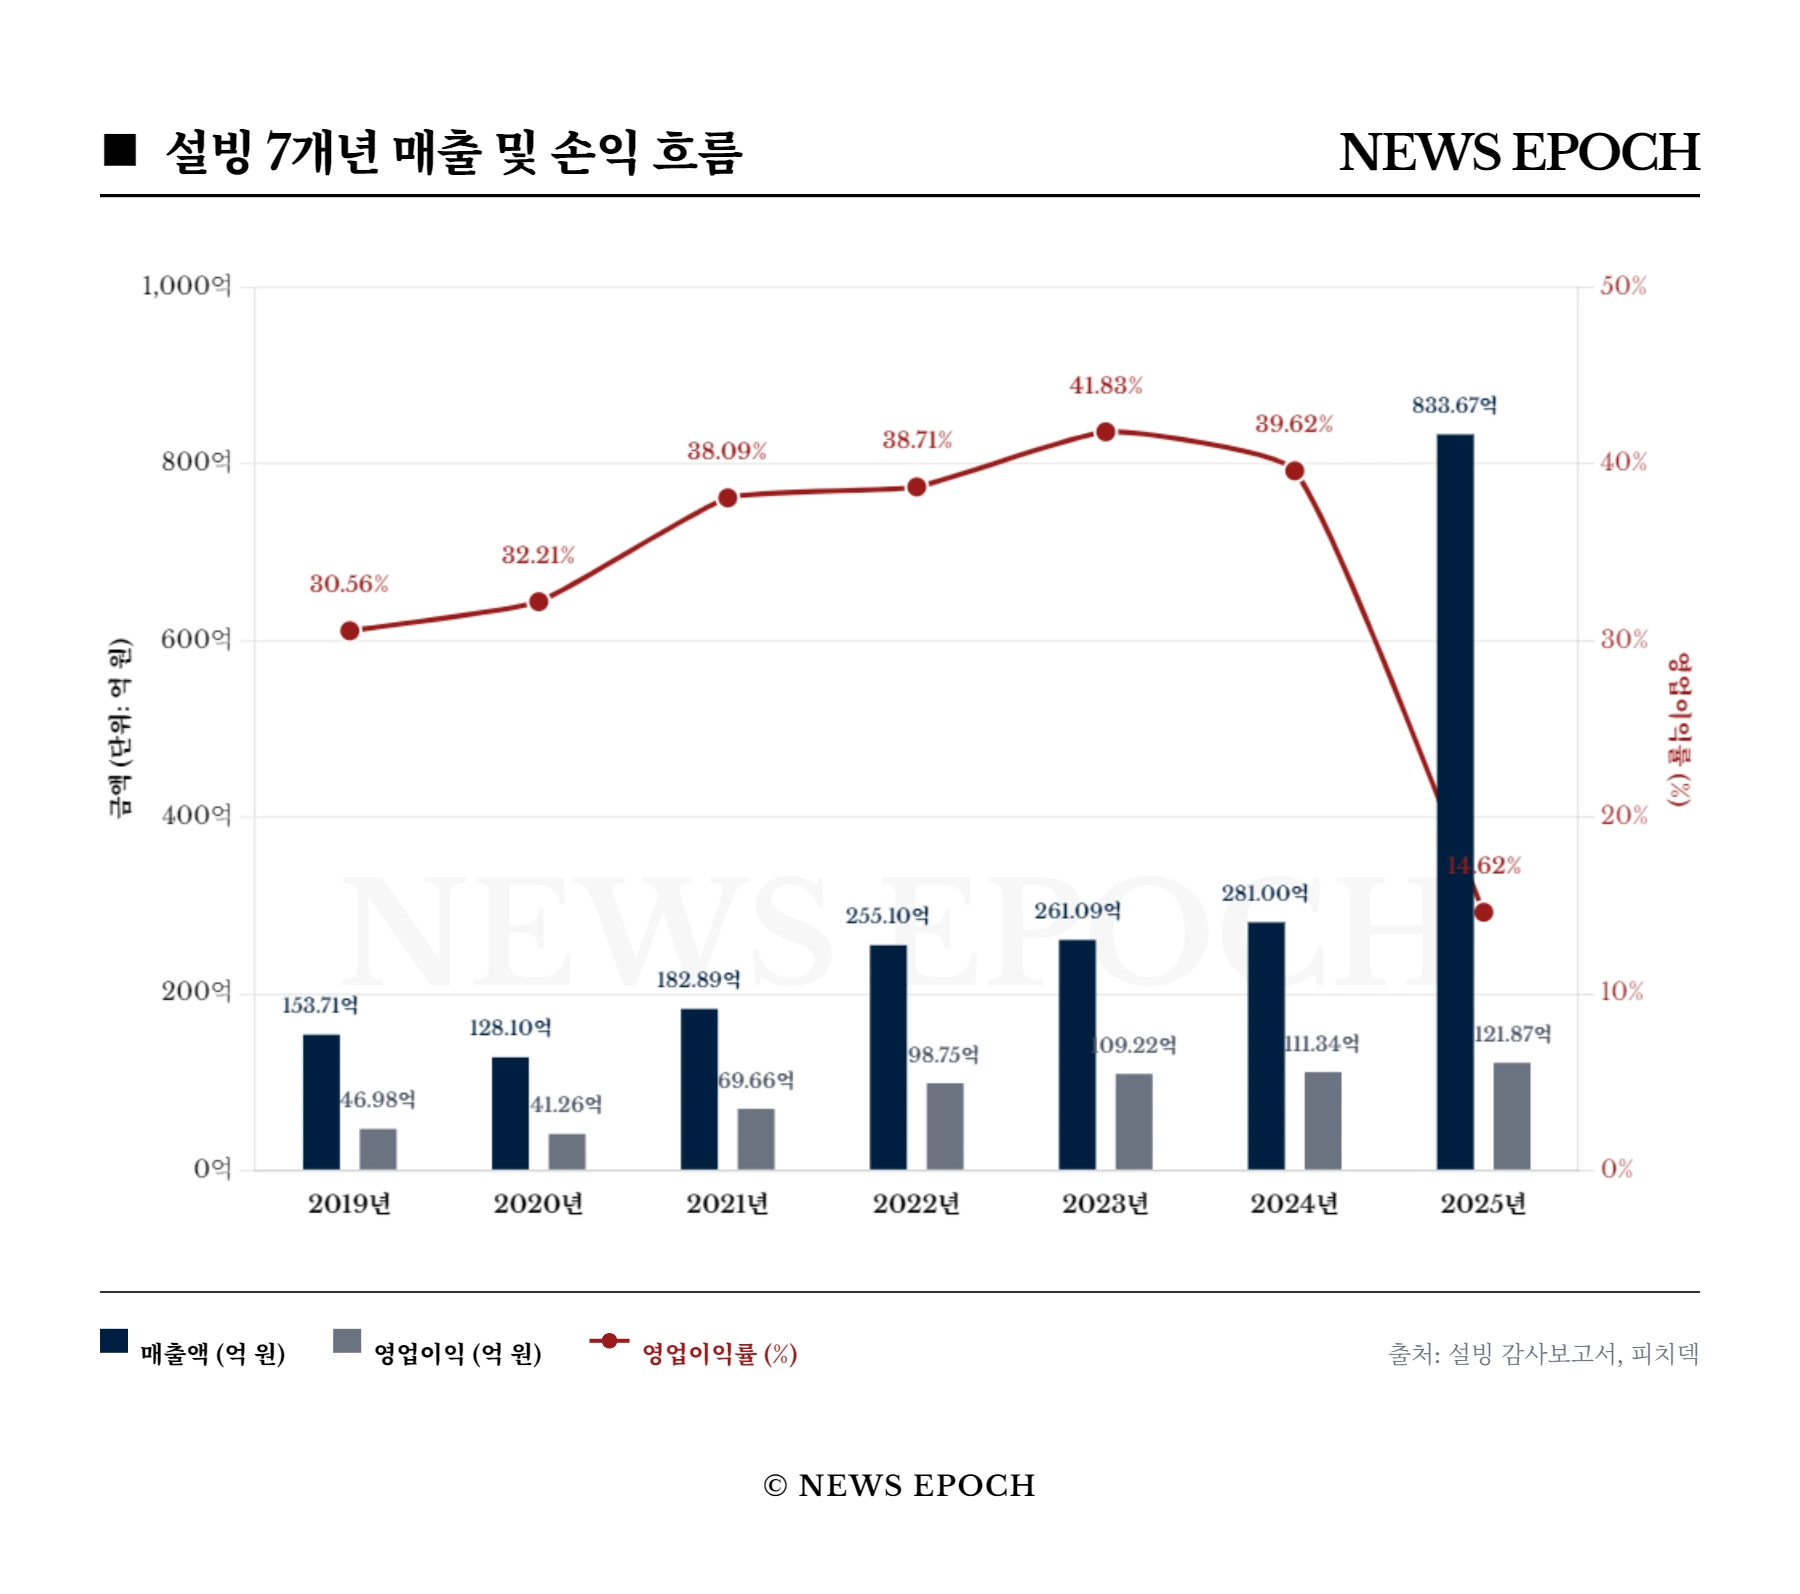
Over the past six years, Sulbing has recorded steady external growth and profit generation. Sales, which were 12.8 billion won in 2020, grew steadily to 28.1 billion won in 2024, and then surged to 83.3 billion won in 2025. Operating profit also showed a steady upward trend after recording 4.1 billion won in 2020, reaching 11.1 billion won in 2024 and achieving 12.2 billion won in 2025.
As a result of the 2025 settlement, Sulbing's sales surged to 83.3 billion won compared to the previous year (28.0 billion won), but operating profit only rose by 10% from 11.1 billion won to 12.2 billion won.
This stark discrepancy between outward growth and profit originates from a fundamental structural change in the cost of sales and the income statement. Until 2024, Sulbing outsourced the supply of goods to franchise stores and received only a commission, recognizing this as 'other sales (net amount)'. However, starting in 2025, the company completely reorganized its distribution structure by taking primary responsibility for purchasing and selling goods, and began recognizing this as 'product sales (gross amount)'. As a result, product sales, which were 6.4 billion won in 2024, exploded to 71.0 billion won in 2025, while commission-based other sales decreased significantly from 17.6 billion won to 6.7 billion won. In other words, the company's actual business size did not triple in a short period, but rather the accounting revenue recognition standard was changed from a commission basis to a gross amount basis.
Decline in Margin Rates and 'Value-Up' as a Franchise Enterprise
As the revenue recognition method was changed to 'gross amount', the proportion of the low-margin distribution business grew, naturally diluting the profit margin. By directly purchasing and supplying goods to franchise stores, the cost of goods sold surged from 5.5 billion won in 2024 to 50.0 billion won in 2025. The total cost of sales also rose alongside it, from 9.5 billion won in 2024 to 55.0 billion won in 2025.
Traces of direct distribution operations are also clearly evident in the SG&A (Selling, General and Administrative) expenses. Logistics costs, which were a mere 47.52 million won in 2024, increased to 4.83 billion won in 2025. Consequently, the operating profit margin against sales dropped from an ultra-high margin of 39.6% in 2024 to the 14.6% level in 2025. This is interpreted as a process of UCK Partners valuing up Sulbing from a simple franchise brand management company to a 'comprehensive food ingredients distribution and logistics franchise enterprise,' and during this process, the outward sales appeared to have grown significantly.
Liquidation of Past Private Transactions and Investment Recovery Through Legal Dividends
During its family management era, Sulbing had inherent limitations typical of unlisted family businesses, such as opaque private transactions and frequent disputes. In the past, the controlling shareholder family, aside from managing the head office, operated private franchise stores such as 'Sulbing Konkuk Univ. Branch Co., Ltd.' and 'Sulbing Konkuk Univ. Branch 2 Co., Ltd.', continuing related-party transactions worth hundreds of millions of won with the head office. However, in 2021, the head office liquidated and absorbed these stores (merger without new shares), legally and completely resolving the issue of the owner family's private store transactions.
Furthermore, as of the end of 2020, short-term loans provided to controlling shareholders and others reached 1.34 billion won, and opacity in corporate fund management existed, such as treating 600 million won of this as uncollectible receivables and expensing it (bad debt expense). During the family management period, legal disputes with franchisees and partner companies were also frequent, resulting in an annual expenditure of 100 to 380 million won under the pretext of compensation, and in 2020, provision for litigation liabilities was accumulated to the level of 860 million won.
Right after the acquisition in 2023, UCK Partners artificially severed and liquidated these related-party receivables and payables, making the company transparent. This improvement in basic fundamentals became a strong foundation for smoothly carrying out large-scale cash dividends without any noise. As of the end of 2023, when UCK acquired it, Sulbing's unappropriated retained earnings reached 43.0 billion won. In the following year, 2024, Sulbing not only transferred the simply accumulated profits but also 5.66 billion won of capital reserves (paid-in capital in excess of par value) formed through past capital transactions into retained earnings, and then paid out 30.2 billion won, which is triple the net profit of that year (10.1 billion won), as its first cash dividend. In 2025, it again distributed 22.0 billion won, which is more than double the net profit of the previous year, carrying out a full-scale investment recovery (recapitalization).
Overseas Expansion and Future Outlook
Along with these internal reorganizations and transparency efforts, overseas expansion is also showing signs of going into full swing. In the 2025 audit report, 'Sulbing USA LLC' (100% stake, acquisition cost 14.65 million won), which has Sulbing Franchise LLC in charge of the US franchise business under it, was newly disclosed as the first overseas subsidiary.
Industry attention is focused on whether UCK Partners, which previously acquired the milk tea brand 'Gong Cha' and achieved a successful sale profit of over 6 times the principal in just 5 years, will write another success story through Sulbing, which has gone through governance transparency and distribution structure reorganization.
Company financial data, investment reports, and startup analysis — all in one place
Explore PitchdeckCurated news, every week — straight to your inbox
Every Friday · Unsubscribe anytime