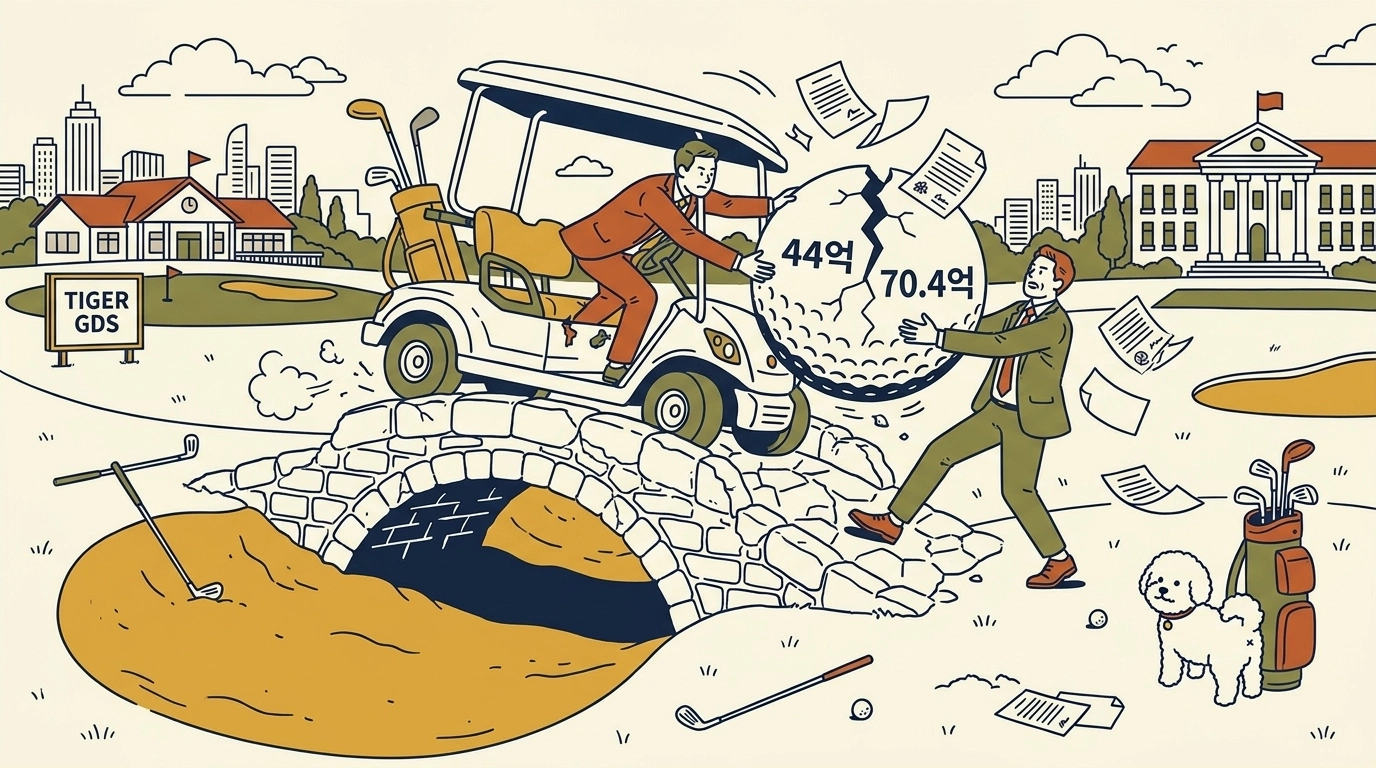
Co-defendants Include Business Partner and Its CEO at the Time of the Transaction
Global golf booking platform operator AGL has filed a lawsuit against a business partner and the company's CEO at the time of the transaction to recover the purchase price for golf products. The current claim amount is 501 million won, but the company plans to expand the claim to approximately 4.4 billion won in the future.
This lawsuit is not a case where AGL is the defendant, but rather one where it is acting as the plaintiff to recover a paid purchase price. AGL evaluated the recoverability of the related receivables as low and has already recognized 7.04 billion won as a loss. While the future financial condition could change significantly depending on the outcome of the lawsuit, the financial burden is not small, as the company is generating annual losses of nearly 10 billion won in its core business independent of the lawsuit.
A Platform Connecting Golf Courses and Sales Channels
Founded in 2019, AGL is a golf-tech company that connects golf courses with sales channels such as golfers and travel agencies. It operates 'Tiger GDS,' which applies the Global Distribution System (GDS)—typically used for flight and hotel bookings—to golf course tee time reservations.
The structure allows external sales channels, such as travel agencies and online platforms, to search, book, and pay for tee times by time slot when a golf course connects its available tee times to AGL's system. AGL also operates its own booking platform, Tiger Booking. The company categorizes its golf product revenue into 'Tee Time' and 'Stay & Play.' Tee Time refers to revenue from selling time-specific products for rounds at specific golf courses through the golf GDS. Stay & Play is a product that combines golf tee times with accommodations. Separately, revenue generated from golf GDS usage fees and payment services is classified as subscription and payment fees.
Co-defendants Include Business Partner and the 'Then-CEO'
According to AGL's 2026 audit report, during the current term, the company filed a lawsuit for the return of the purchase price at the Seoul Central District Court, naming a business partner and the company's then-CEO as defendants. The current claim amount is 501 million won. AGL explained in the audit report that this is a partial claim and stated that it plans to expand the claim amount to approximately 4.4 billion won in the future. As of July 29, when the audit report was finalized, the trial is ongoing.
The reason why AGL designated not only the corporate entity but also the then-CEO as an individual defendant was not disclosed. What role the CEO played in the transaction and what legal responsibility AGL is demanding from the CEO as an individual can only be known by verifying additional documents such as the complaint.
Background of the Lawsuit Estimated Through Financial Statements
Although the specific background of the lawsuit has not been disclosed, some circumstances can be estimated through changes in AGL's financial statements. AGL purchased 14.65 billion won worth of golf products from April 2025 to March 2026. Of this, 7.04 billion won had its account changed from inventory to accounts receivable. This means the accounting nature was changed from goods held for sale to money that needs to be returned by the business partner. The company set an allowance for bad debts for the entire 7.04 billion won of these receivables. In effect, they treated the book value of the asset as essentially zero, considering the recoverability to be uncertain.
Summarizing this flow, it is possible that after AGL purchased products combining golf tee times or accommodations, the contract was not executed normally, or a situation occurred where it became difficult to sell the products, leading them to demand the return of the purchase price. However, this is an estimation based on account changes shown in the financial statements. The reasons for the contract cancellation, whether the other party is at fault, and the specific details of the products converted to receivables do not appear in the audit report.
There are also areas that require further verification. The amount changed from inventory to receivables is 7.04 billion won, but the lawsuit claim amount that AGL stated it plans to expand is approximately 4.4 billion won. There is a difference of about 2.64 billion won between the two amounts. It is unconfirmed whether the remaining amount is a receivable from another transaction, if a portion has already been returned or offset, or if a separate recovery process is underway. It is difficult to conclude that the entire 7.04 billion won is the subject of this lawsuit's claim.
Revenue Increased, but Gross Profit Margin at 2.1%
Excluding the lawsuit, AGL's business situation is also not easy. AGL recorded 14.68 billion won in revenue from April 2025 to March 2026. This is a 20.4% increase compared to the 2024 revenue of 12.19 billion won. Although the two periods do not directly follow each other due to a change in the fiscal year, a rough direction can be compared given that both are 12-month results. During the same period, gross profit decreased from 1.51 billion won to 310 million won. The gross profit margin dropped from 12.4% to 2.1%. The outward size has grown, but the remaining profit after supplying products and services has significantly decreased.
Selling and administrative expenses increased from 7.57 billion won to 10.23 billion won. Accordingly, the operating loss expanded from 6.06 billion won to 9.92 billion won. The net loss also increased approximately threefold, from 5.65 billion won to 16.92 billion won. The net loss includes 7.04 billion won of other bad debt expenses set against receivables. However, even excluding this, a loss of approximately 9.88 billion won remains. This means that it is difficult to explain the company's deficit solely through lawsuit-related losses.
88.5% of Revenue Comes From Accommodation Combined Products
Most of AGL's current revenue was generated from Stay & Play products, which combine golf tee times with accommodations. From April 2025 to March 2026, Stay & Play revenue was 12.99 billion won, accounting for 88.5% of total revenue. Tee Time revenue, which sells golf course round time slots, was 1.66 billion won, representing 11.3%.
On the other hand, subscription and payment fee revenue, such as golf GDS usage fees and payment services, amounted to just 30 million won, accounting for a mere 0.2% of total revenue. These figures were calculated based on the revenue breakdown in the audit report disclosed by AGL.
While AGL outwardly emphasizes its golf GDS platform, most of the revenue on the current financial statements comes from the sale of golf and accommodation combined products rather than platform usage fees. If a company directly purchases golf products and recognizes them as inventory and cost of goods sold, the revenue scale can appear larger than that of a simple brokerage platform. Conversely, the likelihood of the company directly bearing the risks of unsold inventory, advance payments, and counterparty contract defaults and refunds also increases.
The current purchase price return lawsuit also likely occurred during this process of purchasing and distributing products. However, it has not been confirmed whether the transaction in question is related to Tee Time or Stay & Play products.
39 Billion Won in External Investment... 36.14 Billion Won in Accumulated Deficit
AGL has raised a total of 39 billion won from external investors over three rounds. It attracted 2.4 billion won at 5,000 won per share in 2021, and 6.6 billion won at 8,000 won per share in 2022. In the Series B round conducted from November 2023 to March 2024, it raised 30 billion won at 17,000 won per share.
Participants in the Series B round included KB Investment, Shinhan Venture Investment, Hana Ventures, Woori Venture Partners, Korea Development Bank, SV Investment, TS Investment, and Kolon Investment. The estimated enterprise value for Series B is approximately 80.8 billion won.
At the end of March 2026, the sum of capital stock and share premium is 42.21 billion won. The accumulated deficit has grown to 36.14 billion won, leaving 6.07 billion won in equity capital. Although it is not yet in a state of capital impairment, equity capital has decreased by 73.6% from 22.99 billion won a year ago. Liquid assets, combining cash and short-term financial instruments, amount to 11.05 billion won. At the same time, interest-bearing borrowings were tallied at 9.38 billion won. Of this, 9 billion won is a short-term borrowing from Woori Bank backed by a guarantee from the Korea Technology Finance Corporation in October 2025.
The company used 11.07 billion won of cash in operating activities during the corresponding fiscal year. Although it cannot be concluded that the investment funds were directly used for the purchase contract that is the subject of this lawsuit, if the current deficit and cash outflow continue, there is a possibility that additional fundraising or profitability improvement will be necessary.
The Redeemable Convertible Preference Shares (RCPS) held by investors have a condition allowing them to request redemption at an amount applying a 5% annual compound interest rate three years after payment. The investments from 2021 and 2022 have entered the redeemable period. However, because the company is currently in a state of accumulated deficit, the actual redeemability may vary depending on distributable profits and contract conditions.
Losses From Defeat Pre-Reflected... Even With a Win, Core Business Improvement Is Needed
AGL has already recognized the 7.04 billion won of receivables as a loss. Therefore, even if they lose the lawsuit, it is unlikely that the same amount will occur again as a lump-sum loss. However, the cash flow loss of not actually recovering the purchase price would be confirmed. Conversely, if they win the lawsuit and recover 4.4 billion won, profit and equity capital could increase through the reversal of the allowance for bad debts. The 4.4 billion won corresponds to approximately 72.5% of the 6.07 billion won equity capital at the end of March 2026.
A winning verdict and actual recovery must also be distinguished. If the business partner lacks sufficient payment ability, cash recovery could be delayed or become difficult even if AGL wins the lawsuit. It is not possible to judge the business partner's financial condition or payment ability based solely on the current data.
AGL was selected for the preliminary unicorn special guarantee in 2025 and continues to expand its business, such as launching the AI travel agent 'Tavy Golf' this July. However, the performance of the new businesses was not reflected in the financial statements at the end of March 2026.
Ultimately, AGL's future financial condition relies on two variables: the recovery of the lawsuit funds and the profitability of its core business. Recovering 4.4 billion won from the lawsuit could reinforce the financial structure, but if the annual operating loss of approximately 10 billion won continues, recovering the lawsuit funds alone will not be sufficient. Whether the company can secure adequate profits from product sales and expand platform fee revenue remains a more fundamental challenge.
Company financial data, investment reports, and startup analysis — all in one place
Explore PitchdeckCurated news, every week — straight to your inbox
Every Friday · Unsubscribe anytime