Once the first domestic coffee franchise to surpass 1,000 stores, Caffe Bene is challenging the low-cost coffee market again. It plans to expand its franchise business spearheaded by 'Caffe Bene Express,' which features lower prices and smaller store sizes compared to the existing Caffe Bene.
According to the Fair Trade Commission's Franchise Business System, Caffe Bene Co., Ltd. newly registered the information disclosure document for Caffe Bene Express on the 21st. By lowering the price of an Americano to 2,000 won, it targets the low-cost coffee market dominated by MEGA MGC COFFEE, Compose Coffee, and Paik's Coffee. Caffe Bene was once a brand symbolizing the growth of domestic coffee franchises. However, due to unreasonable store expansion and sluggish overseas business, its management rights were handed over to private equity funds and overseas investors, and it even underwent corporate rehabilitation proceedings in 2018. With the state of complete capital impairment still continuing, attention is focused on whether Express can serve as a stepping stone for its comeback.
Start-up Cost of 89.9 Million Won for a 33㎡ Store... Opening Record is Still '0'
Caffe Bene Express is a brand targeting small stores and takeout demand. The standard store area stated in the information disclosure document is 33㎡, or about 10 pyeong. The total cost to be borne by the franchisee is 89.9 million won. It consists of a franchise fee of 3.3 million won, training fee of 3 million won, deposit of 2.2 million won, and other costs including interior and equipment amounting to 81.4 million won. The interior cost based on 33㎡ is 19.8 million won, which is 1.98 million won per 3.3㎡. The initial franchise contract period is 3 years, and the renewal period is 1 year.
Caffe Bene Express is at the stage where it has just registered its information disclosure document. The directly managed and franchise stores as of the end of 2025 stated in the information disclosure document are both 0. This means there is no data yet to judge actual store sales, closing rates, or franchise profitability. The initial investment burden is also not lower than that of competing brands. In the 2025 registered information disclosure document, the franchisee's burden for MEGA MGC COFFEE based on 33㎡ is 78.47 million won. Comparing on the same basis, Caffe Bene Express is 11.43 million won, or about 14.6% higher. However, since the scope of equipment, initial supplies, and separate construction varies by brand, the actual opening cost may differ depending on the store's situation.
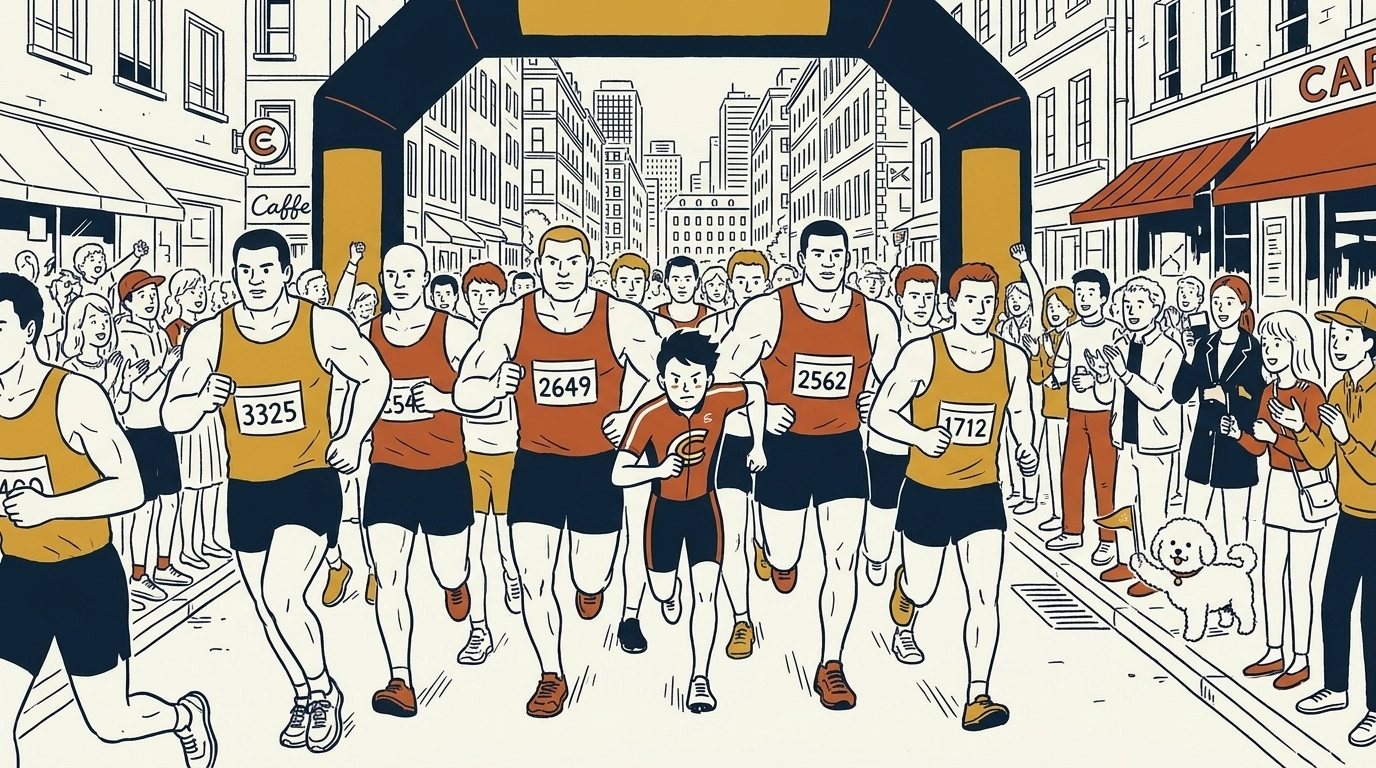
The market Caffe Bene Express needs to target is already in a state where large low-cost coffee brands have secured scale. Based on the 2025 registered information disclosure documents, the number of franchise stores is 3,325 for MEGA MGC COFFEE, 2,649 for Compose Coffee, 2,562 for Ediya Coffee, and 1,712 for Paik's Coffee. On the same basis, the existing Caffe Bene has 96 franchise stores and 3 directly managed stores, making a total of 99 stores. Compared to MEGA MGC COFFEE, its number of franchise stores is only about 1/35, and compared to Paik's Coffee, it is only about 1/18.
There is also a difference in the average sales of franchise stores. The average monthly sales of Caffe Bene franchise stores are 16.04 million won, which translates to about 192 million won annually. MEGA MGC COFFEE is 388 million won, Paik's Coffee is 324 million won, and Compose Coffee is 272 million won. Caffe Bene is at the level of 49.5% of MEGA MGC COFFEE, 59.3% of Paik's Coffee, and 70.8% of Compose Coffee, respectively. However, there is no significant difference from Ediya Coffee's average annual sales of 195 million won.
901 Domestic Stores and 99 Overseas... The Flip Side of the '1,000-Store Myth'
After starting its franchise business in 2008, Caffe Bene aggressively increased its stores. On August 19, 2013, it surpassed 1,000 stores by combining 901 domestic stores and 99 overseas stores in 5 countries including the US and China. It was the first case of a domestic coffee franchise exceeding 1,000 domestic and overseas stores combined. Its external size also grew rapidly. Its consolidated sales in 2012 were 220.7 billion won, and operating profit was 6.6 billion won. At the time, it surpassed Starbucks Korea and Ediya Coffee and was evaluated as the representative brand in the domestic coffee franchise market.
However, during its growth process, a high dependence on interior and equipment supply was pointed out as a problem. From November 2008 when it started the franchise business to April 2012, Caffe Bene required 735 franchise stores to deal with the headquarters or designated companies for interior construction and equipment/device supply. The sales Caffe Bene generated from interior and equipment supply during this period were 181.3 billion won. This amounted to 55.7% of total sales during the same period. This means that rather than simply supplying coffee and raw materials, interior and equipment sales resulting from the opening of new franchise stores accounted for a significant part of its growth. In 2014, the FTC issued a corrective order and imposed a penalty of 1.942 billion won for restricting franchisees' choice of transaction partners and passing on telecommunication company partnership discount costs to store owners. At the time, this was the highest penalty ever imposed for violating the Franchise Business Act.
The overseas business pursued alongside store expansion also returned as a burden. Funds were injected into overseas corporations such as the US and China, but they failed to produce the expected results. In 2016, the US subsidiary recorded a net loss of 13.2 billion won. In the same year, Caffe Bene's sales decreased to 81.7 billion won, and it recorded operating losses in the 10 billion won range. Its net loss swelled to 33.6 billion won, entering complete capital impairment. It also sold assets to secure liquidity. In November 2014, Caffe Bene sold its land and office building in Cheongdam-dong, Seoul, and then raised 36.3 billion won through a sale-and-leaseback method. However, this was insufficient to resolve its overseas business and financial burden.
Following K3, Hallyu Ventures Injected 16.59 Billion Won... Not a 'Package M&A'
Caffe Bene's ownership structure changed significantly starting in 2014 when its financial difficulties began in earnest. In 2014, Caffe Bene issued 1,491,300 redeemable convertible preference shares targeting K3 No.5 Private Equity Fund. The issue price was 15,000 won per share, amounting to a total of 22.37 billion won. On December 28, 2015, K3 No.5 converted all of its preferred shares into common shares, securing an 84.2% stake. As the largest shareholder changed to the K3 side, the stake of founder and former chairman Kim Sun-kwon fell from 49.5% to 7.3%. This is the point when Caffe Bene's management rights passed from the founder to a financial investor.
In 2016, foreign capital entered. Hallyu Ventures, jointly established by Singaporean food company Food Empire and Indonesia's Salim Group, acquired new shares of Caffe Bene for 16.59 billion won. Hallyu Ventures' stake became 38.44%, and with the issuance of new shares, the K3 side's stake decreased to 52.02%. Hallyu Ventures continued to provide funding afterwards. After lending a total of 11 billion won in late 2016 and early 2017, it participated in a paid-in capital increase of about 5.8 billion won in June 2017. At the time of the capital increase announcement, the expected stake was 45.8%. However, the stake before the implementation of the rehabilitation plan disclosed by Food Empire during the 2018 rehabilitation process was 44.8%, and the specific reason for the 1 percentage point difference cannot be confirmed in public data.
As management normalization was delayed despite continued capital injections, Caffe Bene filed for corporate rehabilitation proceedings with the Seoul Bankruptcy Court on January 12, 2018. In May of the same year, the court approved a rehabilitation plan to convert 30% of the rehabilitation claims into equity and repay the remaining 70% in cash installments over 10 years. The 12th Bankruptcy Division of the Seoul Bankruptcy Court decided to terminate the rehabilitation proceedings on October 11, 2018. It was about 9 months after filing for rehabilitation. Creditors such as Korea Development Bank also became major shareholders due to the debt-to-equity swap under the rehabilitation plan.
During the debt-to-equity swap process, Hallyu Ventures' stake was adjusted to 37.61%, but it became the largest shareholder as other shareholders' stakes were diluted more significantly. As of the end of 2024, the stakes are Hallyu Ventures 37.6%, Sirius Equity Partners 25.1%, Korea Development Bank related shareholders 11.5%, and other shareholders 25.8%.
Sirius Equity Partners is a company whose name was changed from K3 Equity Partners, which previously invested in Caffe Bene, in October 2017. Currently, Caffe Bene's management is headed by CEO Greta Park, who is also the CEO of Sirius Equity Partners. The largest shareholder is Hallyu Ventures, but the management is handled by existing K3-affiliated executives.
Sales Dropped from 25.8 Billion Won to 4.25 Billion Won in 6 Years... The Failure of a Low-cost Brand 10 Years Ago is Also a Burden
Even after graduating from rehabilitation proceedings, Caffe Bene's external shrinkage continued. Based on the information disclosure document, separate basis sales decreased from 25.8 billion won in 2019 to 18.11 billion won in 2021, 12.45 billion won in 2023, and 7.45 billion won in 2024. The 2025 sales were 4.25 billion won, down 42.9% from the previous year. Compared to 2019, this is an 83.5% decrease over 6 years. Operating losses shrank from 970 million won in 2024 to 230 million won in 2025, and net losses reduced from 1.44 billion won to 520 million won.
This is not the first time Caffe Bene has attempted a low-cost coffee brand. In April 2015, it introduced the first 'Baristella' store near Hongik University Station. It was a takeout-centric store of about 20 pyeong, pricing a super-sized Americano at 2,900 won. However, backlash from existing Caffe Bene store owners followed. It was pointed out that the company might be bypassing the business area restrictions of existing Caffe Bene through a separate brand, and concerns were raised that a second brand could steal customers from existing stores. Caffe Bene eventually scrapped its plan to expand Baristella into an independent low-cost coffee brand and pivoted towards utilizing the existing Caffe Bene brand.
Unlike Baristella over 10 years ago, Caffe Bene Express has put the Caffe Bene name at the forefront. While controversy over bypassing business areas through a separate brand can be reduced, the price difference with existing Caffe Bene stores and internal brand competition could become a new challenge. Low-cost coffee is a market where it is difficult to achieve results with low prices alone. It must lower raw material procurement costs and logistics costs based on a large-scale franchise network, and secure store profitability with high sales volume.
Whether Caffe Bene, which wrote the 1,000-store myth, can get back on the growth track with 2,000 won coffee, and whether it can overcome the conflicts and limitations that arose during its low-cost brand challenge 10 years ago, is the key to this new attempt.
Company financial data, investment reports, and startup analysis — all in one place
Explore PitchdeckCurated news, every week — straight to your inbox
Every Friday · Unsubscribe anytime